Economic sentiment rebounds despite climbing energy prices

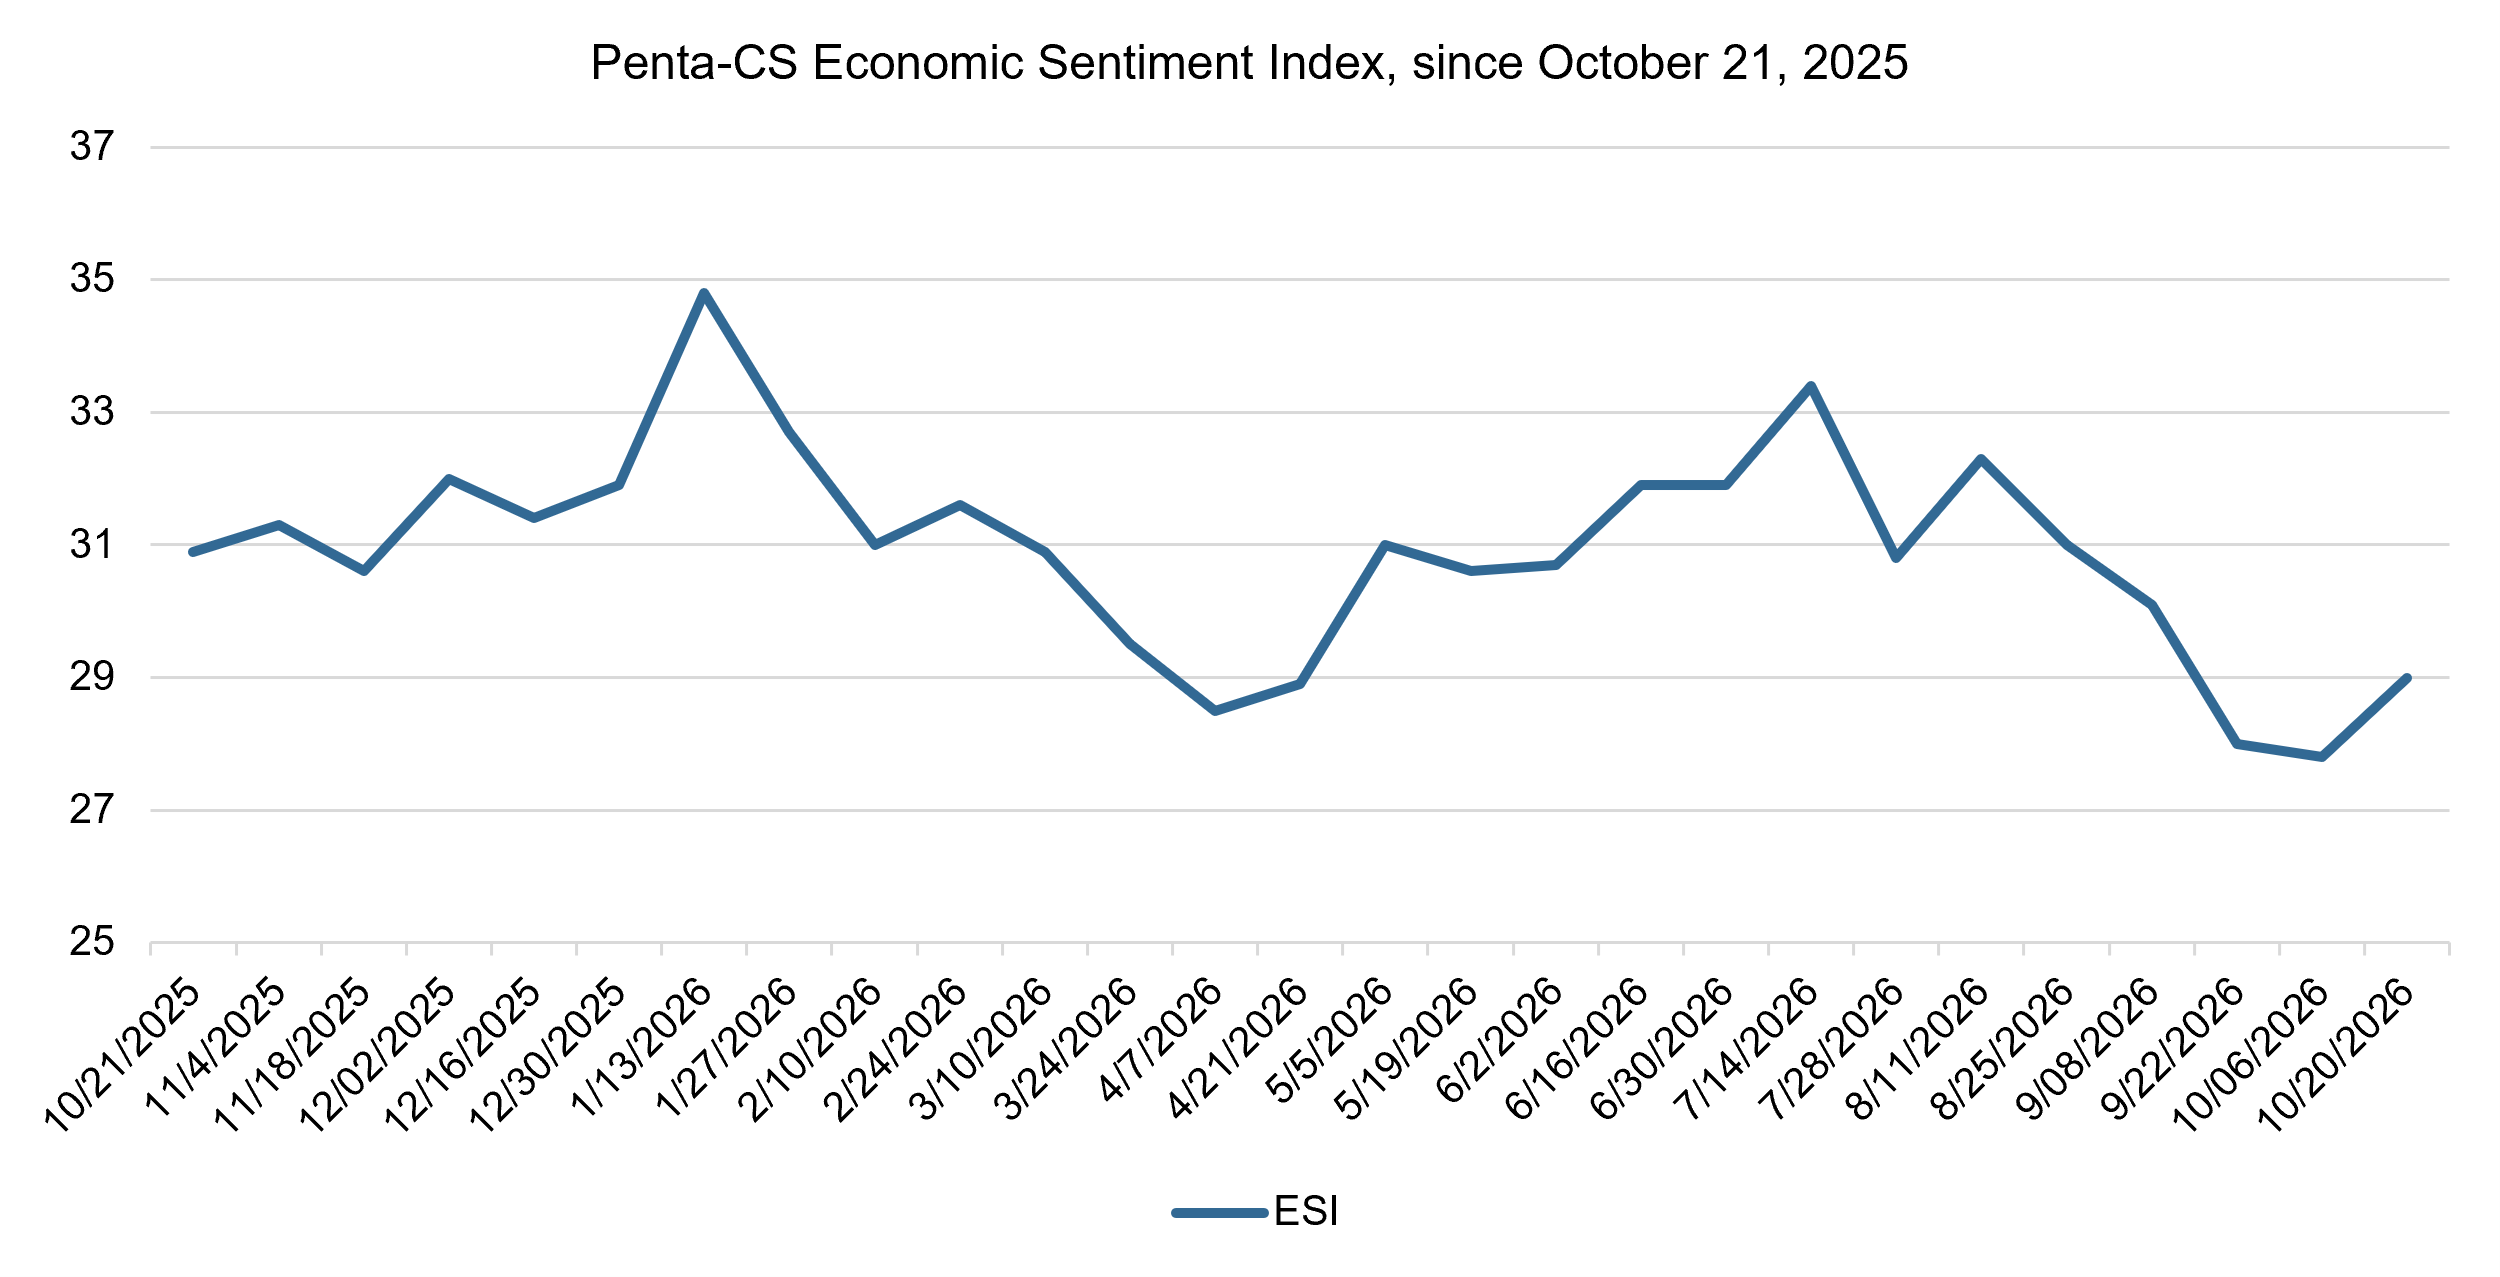
The latest biweekly reading of the Penta-CivicScience Economic Sentiment Index (ESI) increased 1.2 points to 29.0, its first increase after four consecutive declines. The increase came despite accelerating inflation, mortgage rates reaching a three-year high, and renewed volatility in energy markets.
Click to view image.

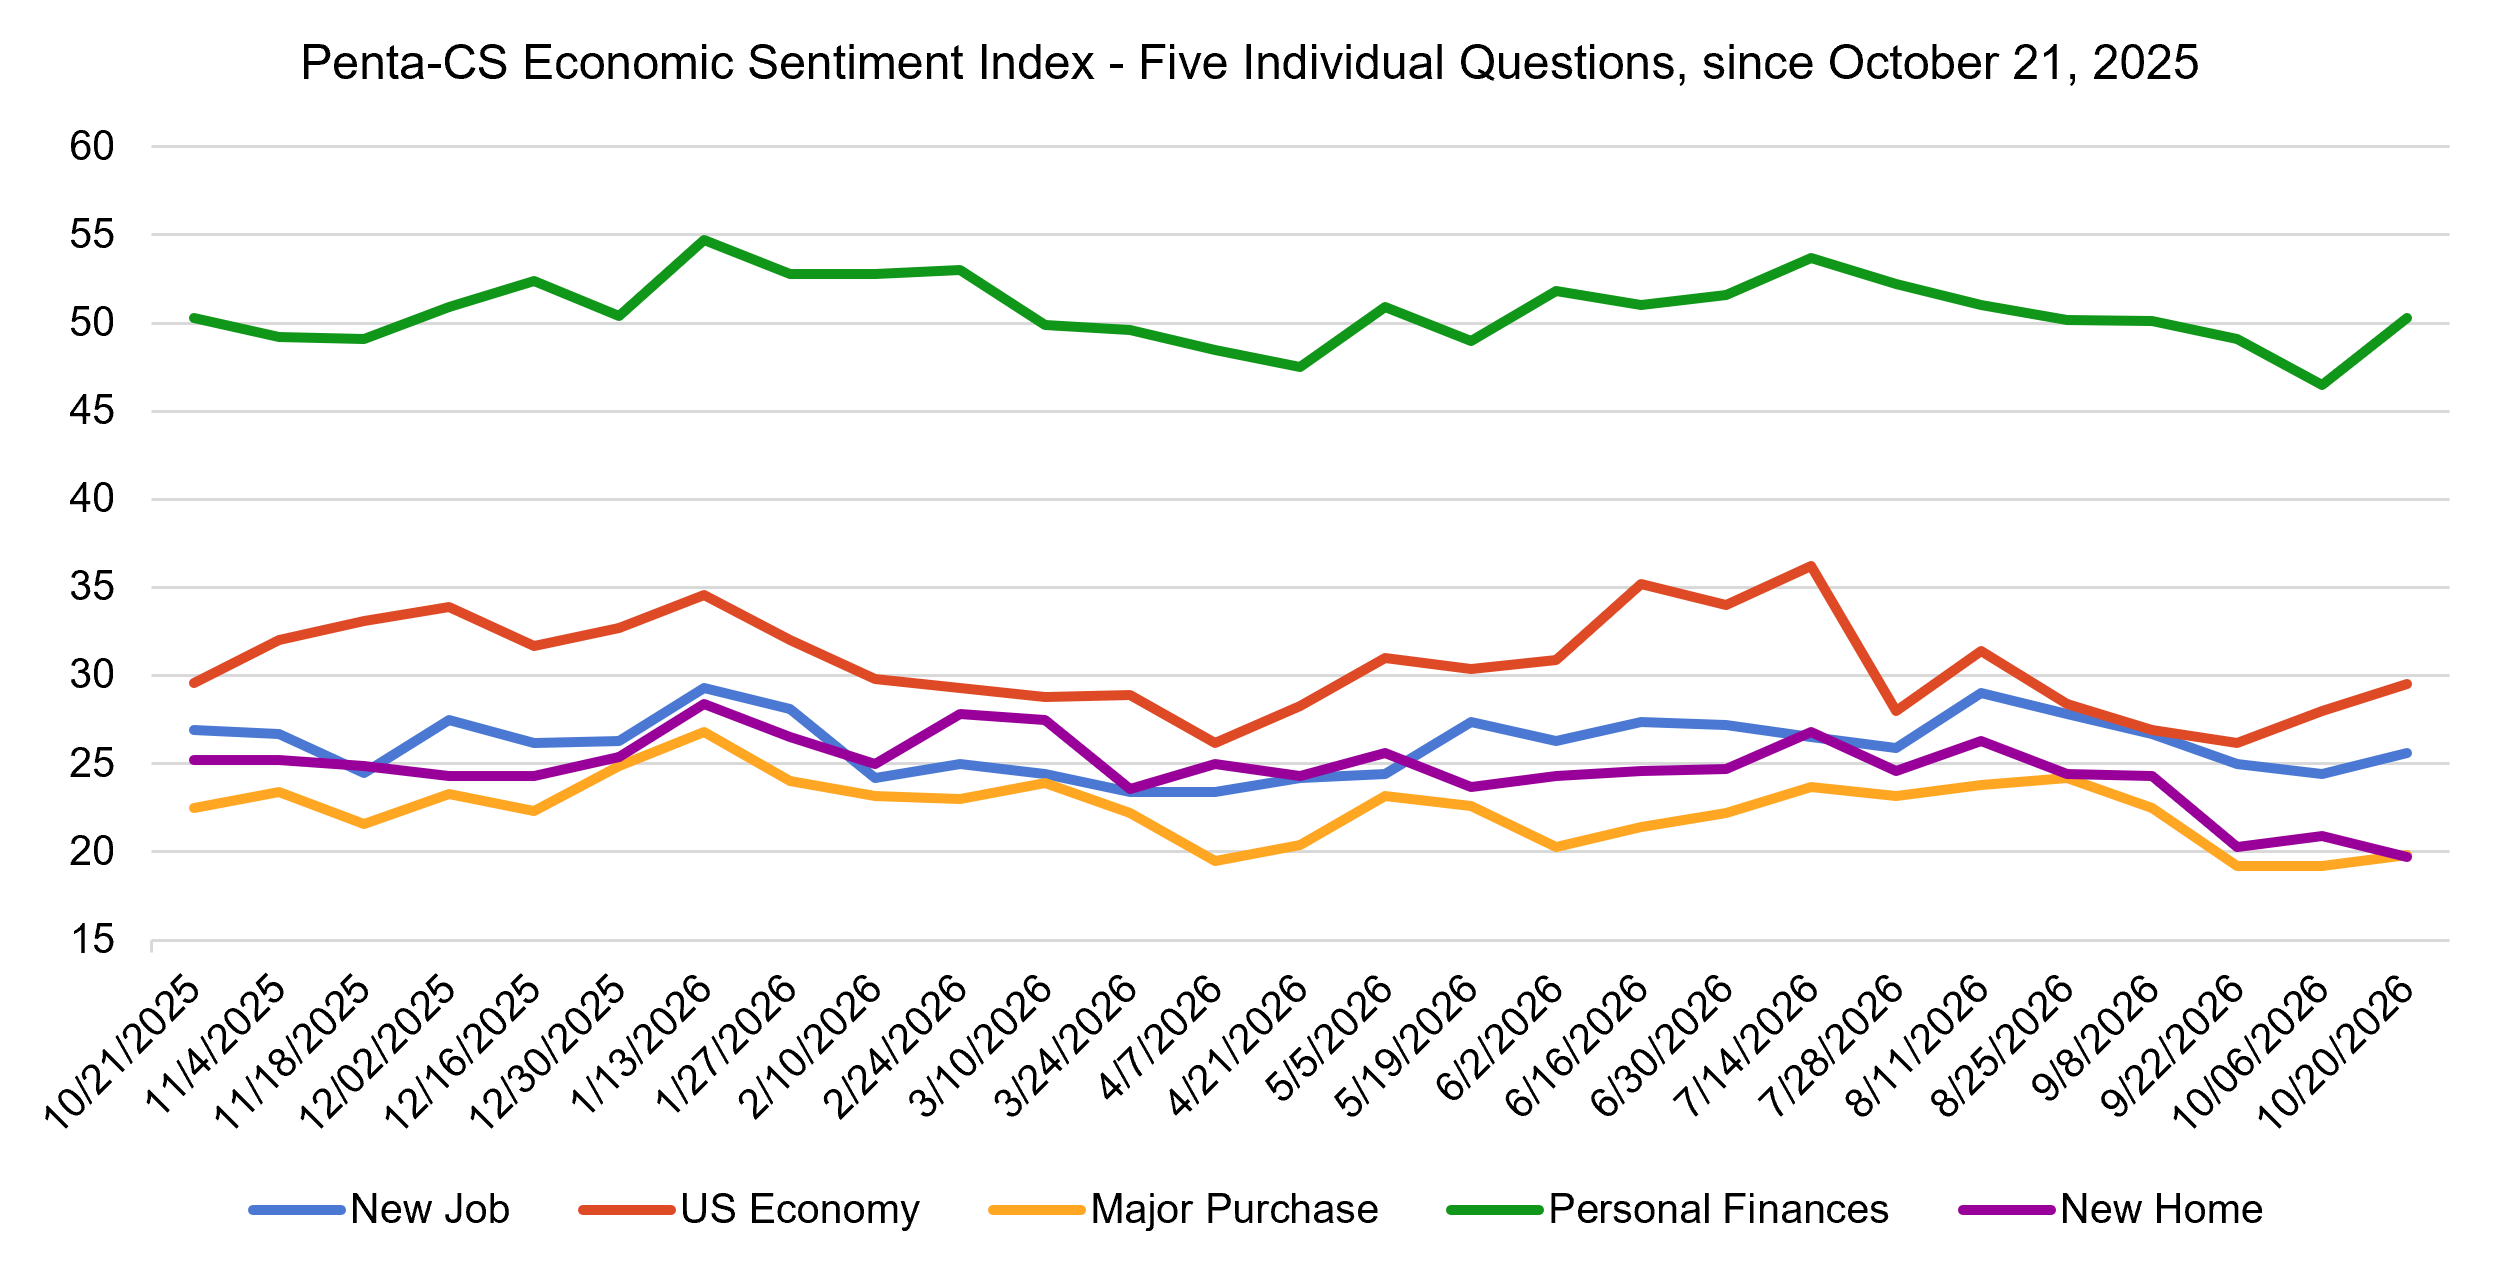
Four of the ESI’s five indicators increased during this period. Confidence in personal finances increased the most, rising 3.8 points to 50.3.

—Confidence in the overall U.S. economy increased 1.5 points to 29.5.
—Confidence in finding a new job increased 1.2 points to 25.6.
—Confidence in making a major purchase increased 0.6 points to 19.8.
—Confidence in buying a new home decreased 1.2 points to 19.7.
Click to view image.

Inflation accelerated in September, exceeding economists’ expectations, as rising energy costs contributed to increased price pressures. The Bureau of Labor Statistics (BLS) reported that the Consumer Price Index (CPI) rose 0.6 percent during the month and 3.7 percent year-over-year, up from 3.4 percent in August. Gasoline accounted for over half of the monthly increase. Renewed attacks on shipping in the Strait of Hormuz pushed Brent crude to $109.86 per barrel on October 16, adding further upward pressure to the energy prices. At the same time, core CPI, which excludes volatile food and energy prices, also rose to 2.6 percent year-over-year from last month’s 2.4 percent, indicating that price pressures extended beyond energy. Mark Zandi, chief economist at Moody’s, said the report showed inflation is “uncomfortably strong.” 

Minutes from the Federal Open Market Committee’s (FOMC) September meeting, released on October 7, showed that 16 of 18 officials expected another interest rate increase before the end of the year as inflation remained elevated. However, the Fed’s latest Beige Book report painted a mixed picture of economic conditions across the country. Most Federal Reserve districts reported little or no change in consumer spending and employment, while three reported robust price growth. These findings underscore the challenge facing the Fed as it weighs persistent inflation against signs of slowing economic activity.

Mortgage rates continued to climb during the period, adding to affordability challenges for prospective homebuyers. Freddie Mac reported that the average 30-year fixed mortgage rate rose to 7.4 percent during the week ending October 8, hitting a three-year high. Higher borrowing costs continued to weigh on the housing market, as the National Association of Realtors (NAR) reported that existing-home sales rose just 1.5 percent in September, with August and September marking the two slowest months for sales this year. Meanwhile, the median existing-home price rose 1.3 percent from a year earlier to $417,500, keeping affordability strained even as sales slowed.
Click to view image.

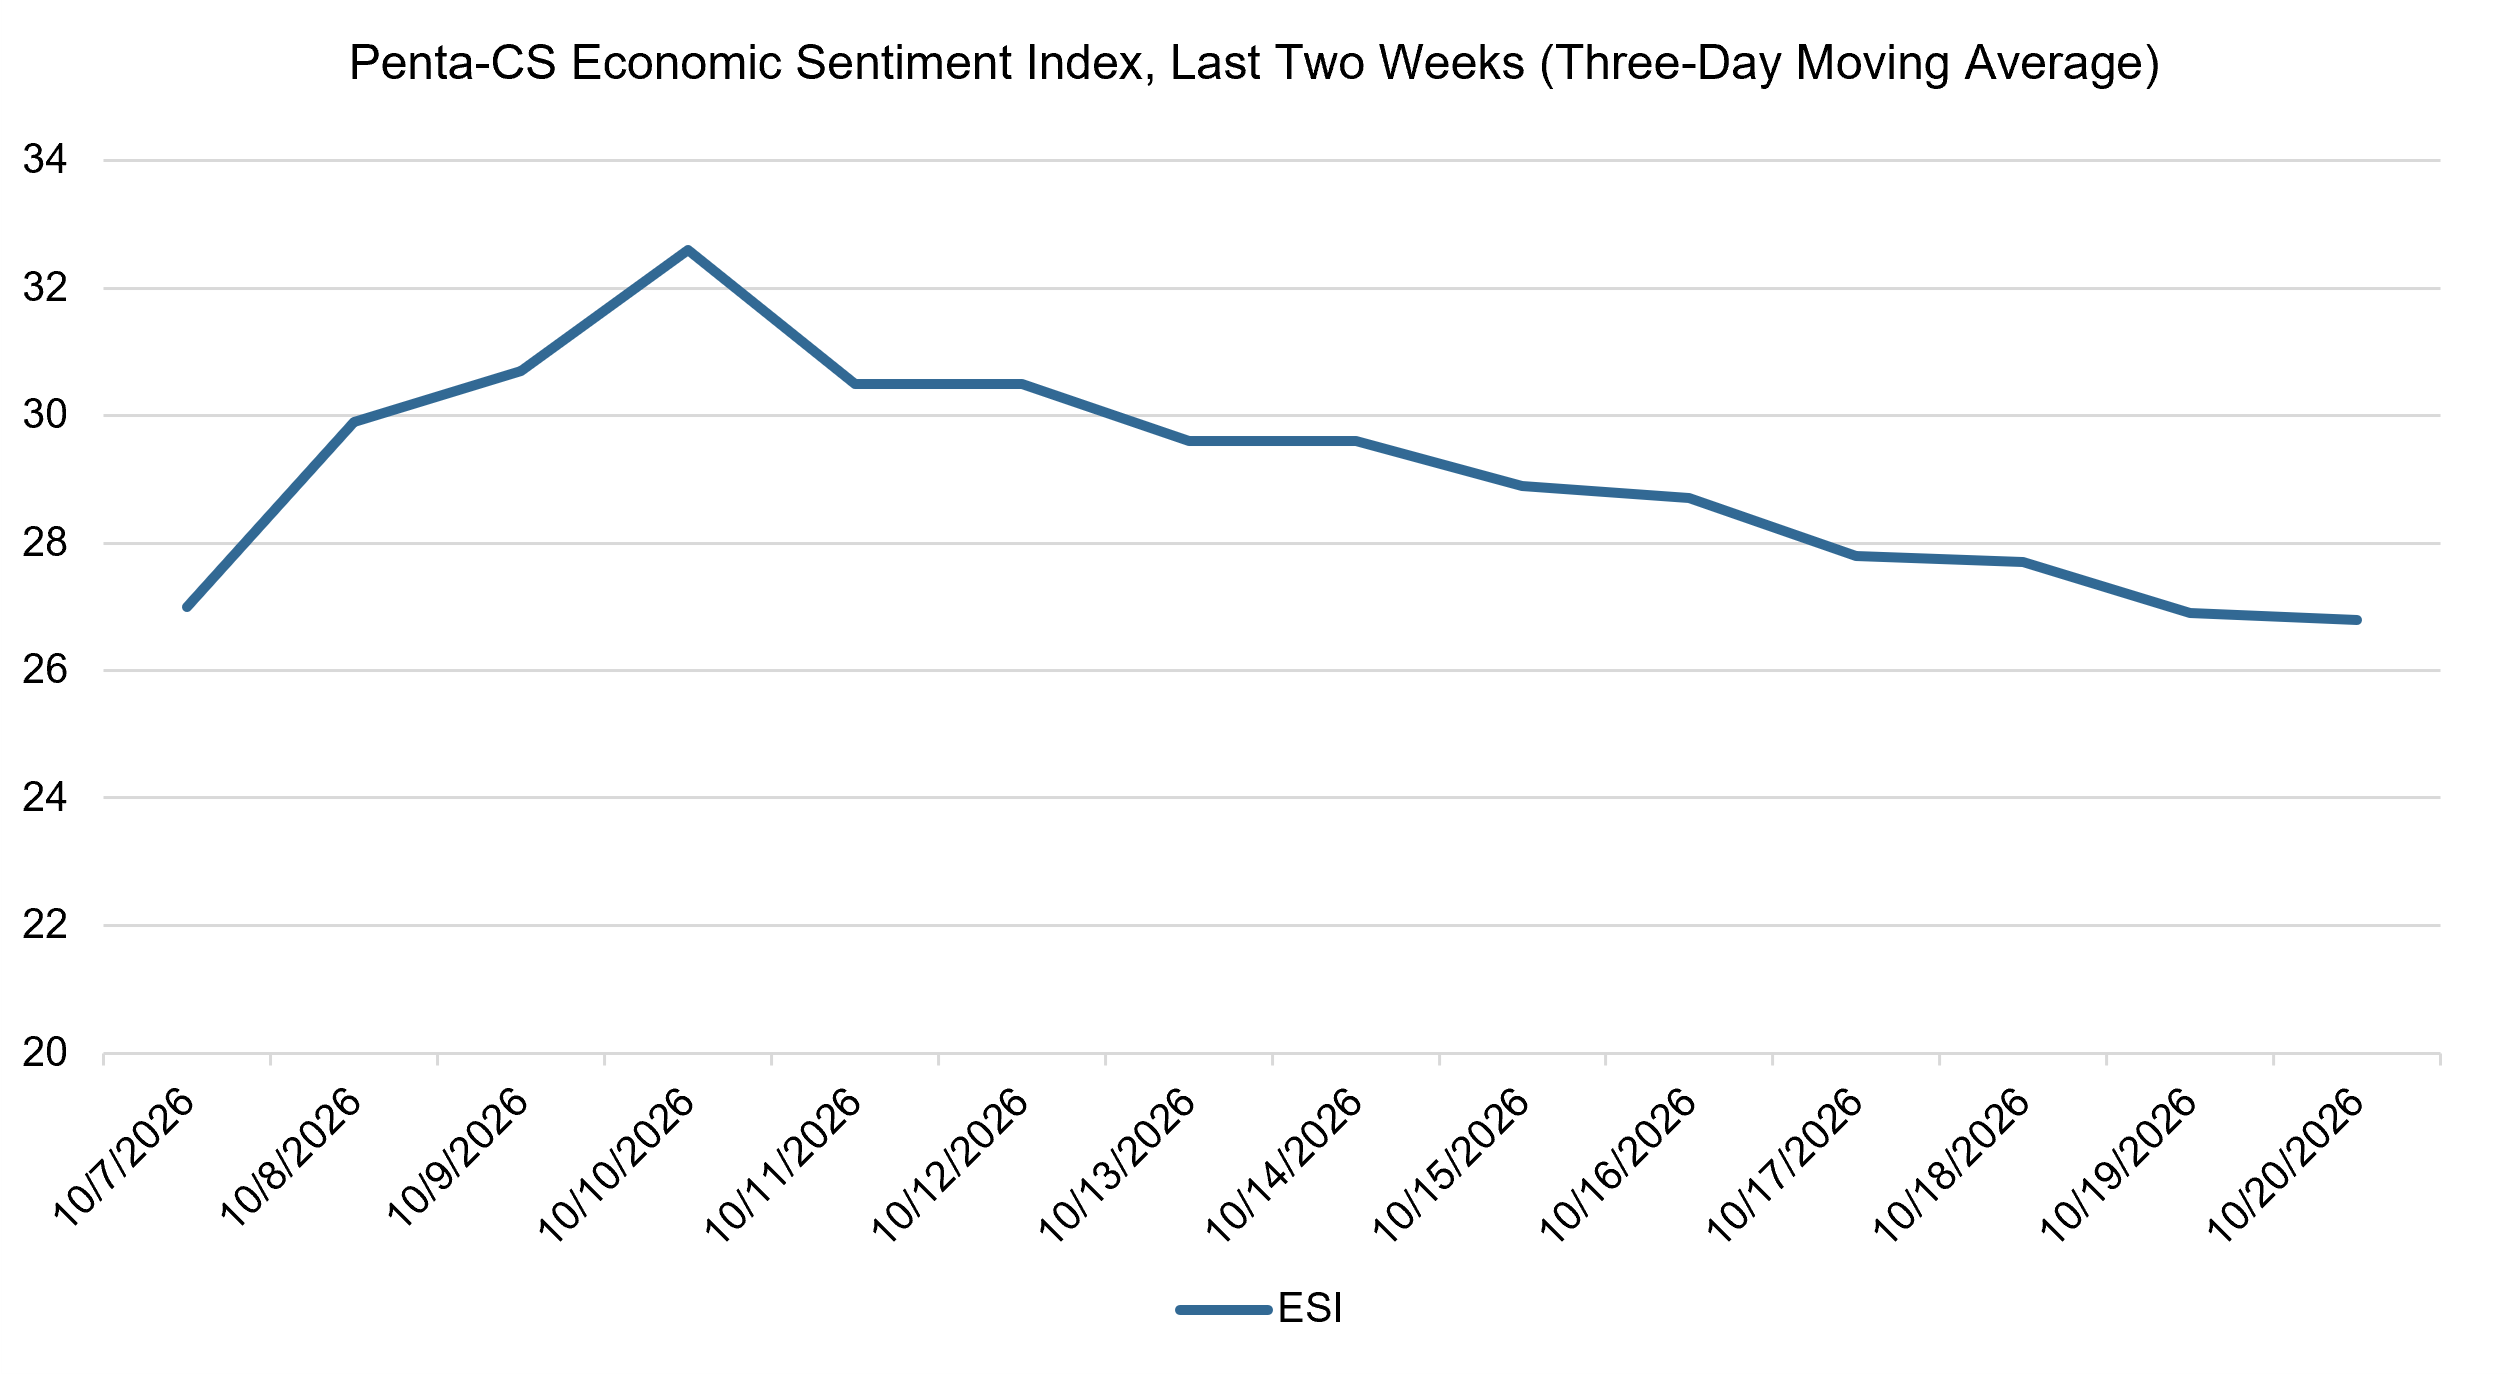
The ESI’s three-day moving average peaked early before steadily declining to its low for the period. It began at 27.0 on October 7 before rising sharply the next day to 29.9. It then rose to a high of 32.6 on October 10 before falling to a low of 26.8 on October 20 to close out the session.

The next release of the ESI will be on Wednesday, November 4, 2026.
Economic sentiment sinks again to new all-time low

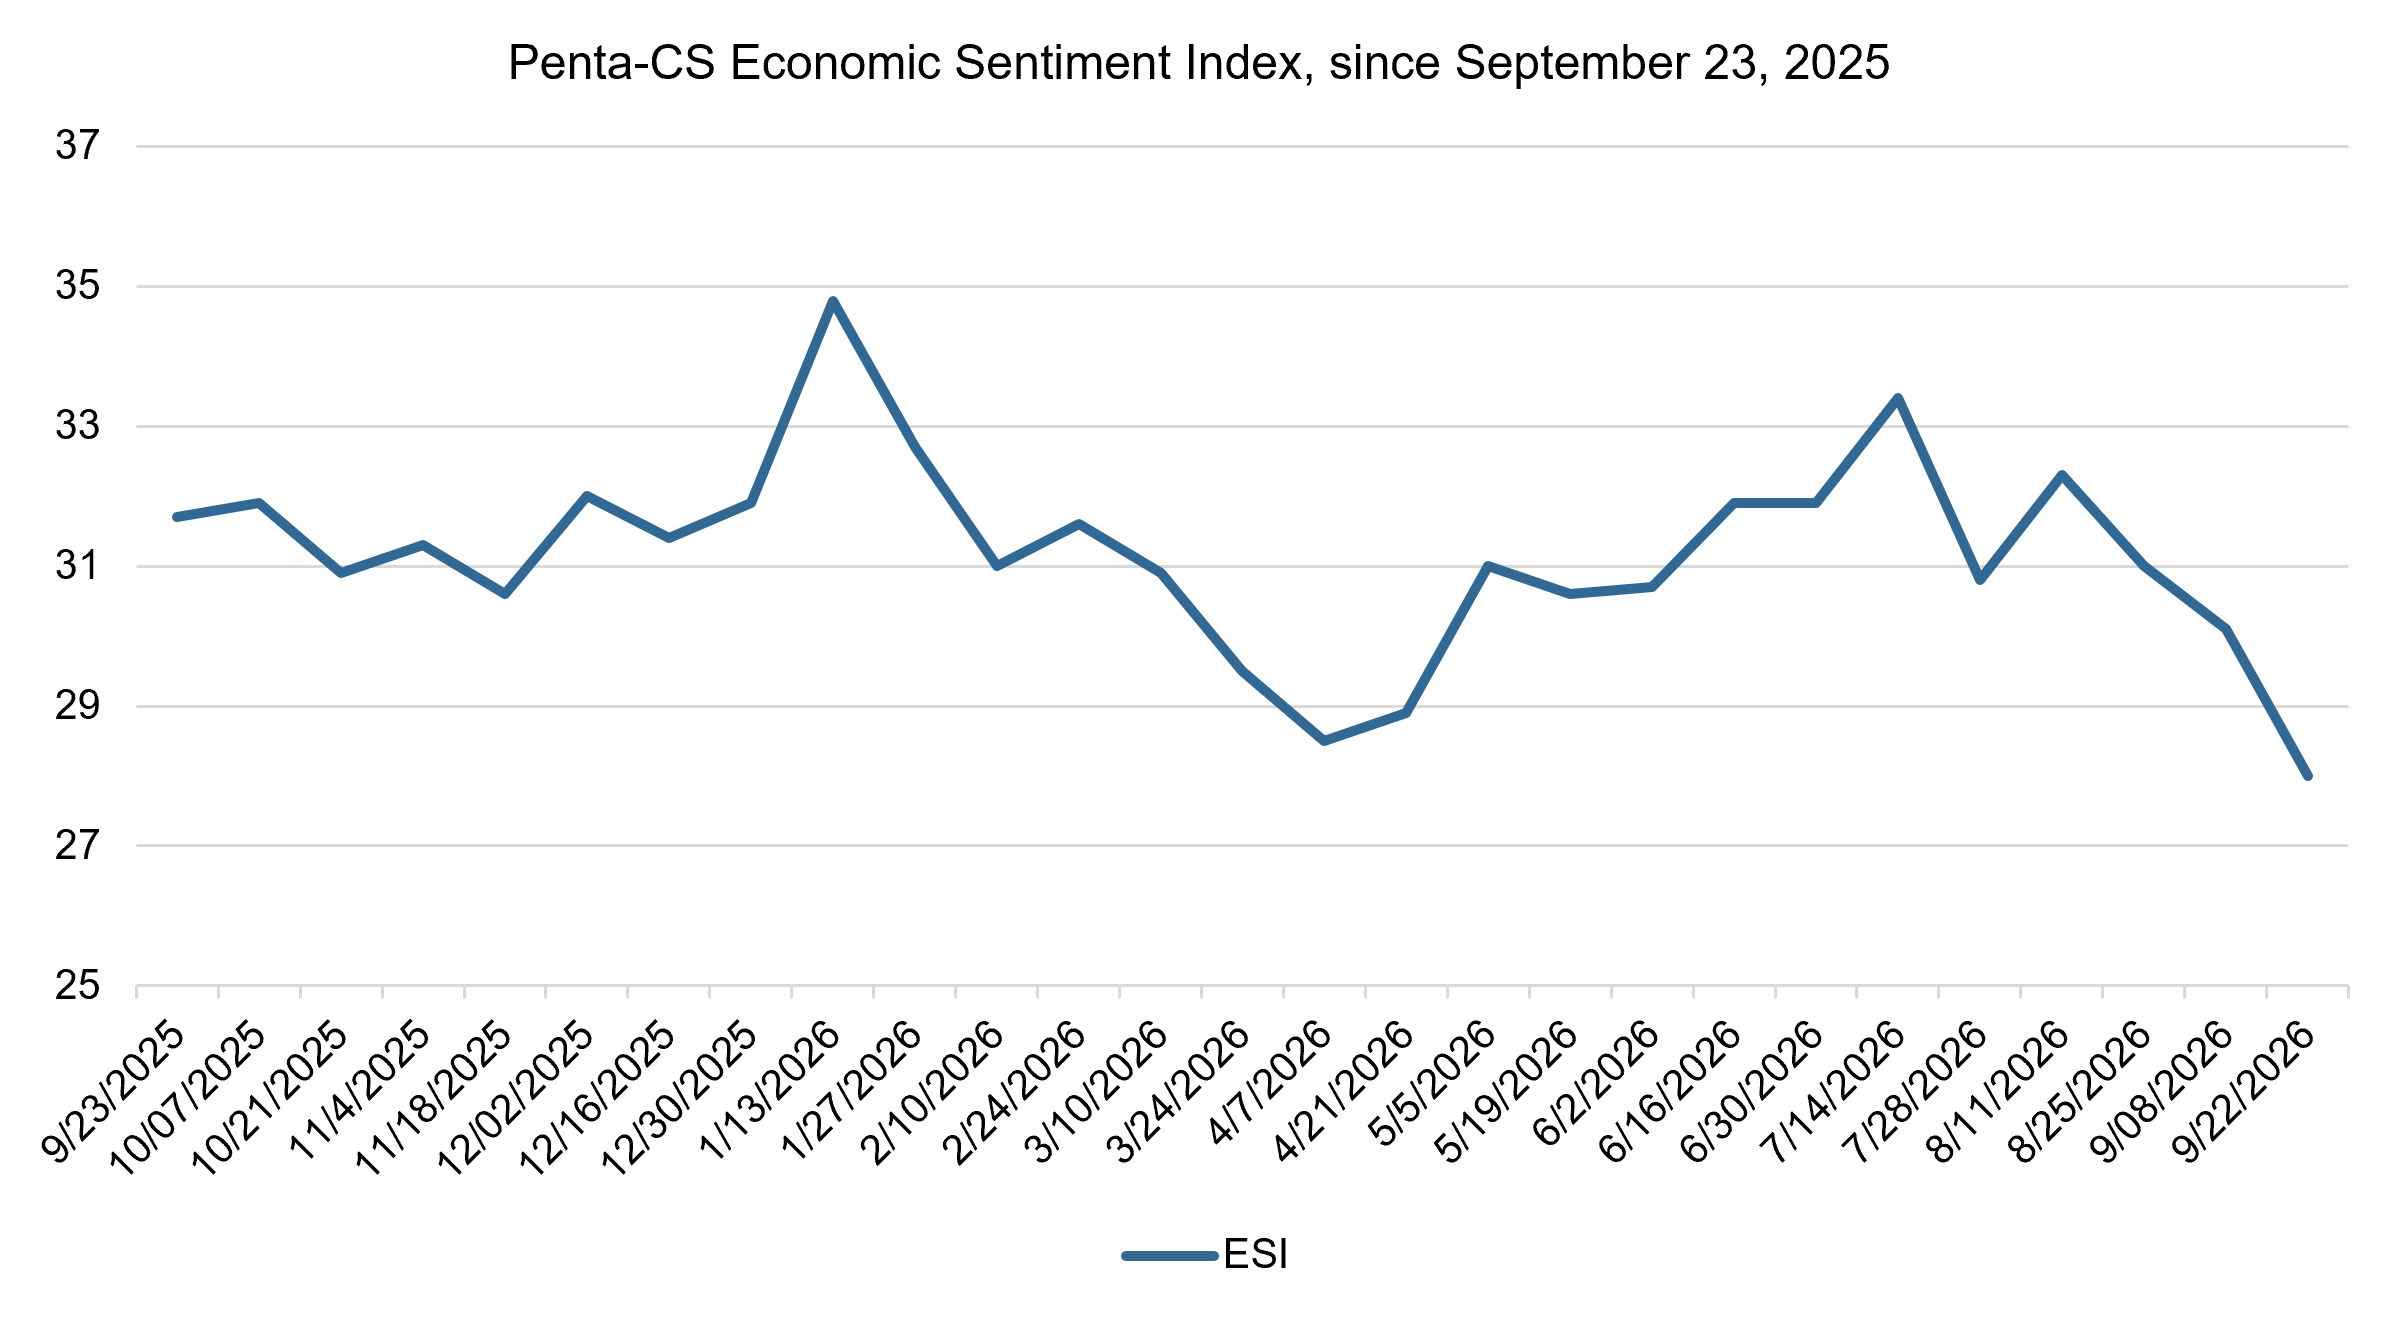
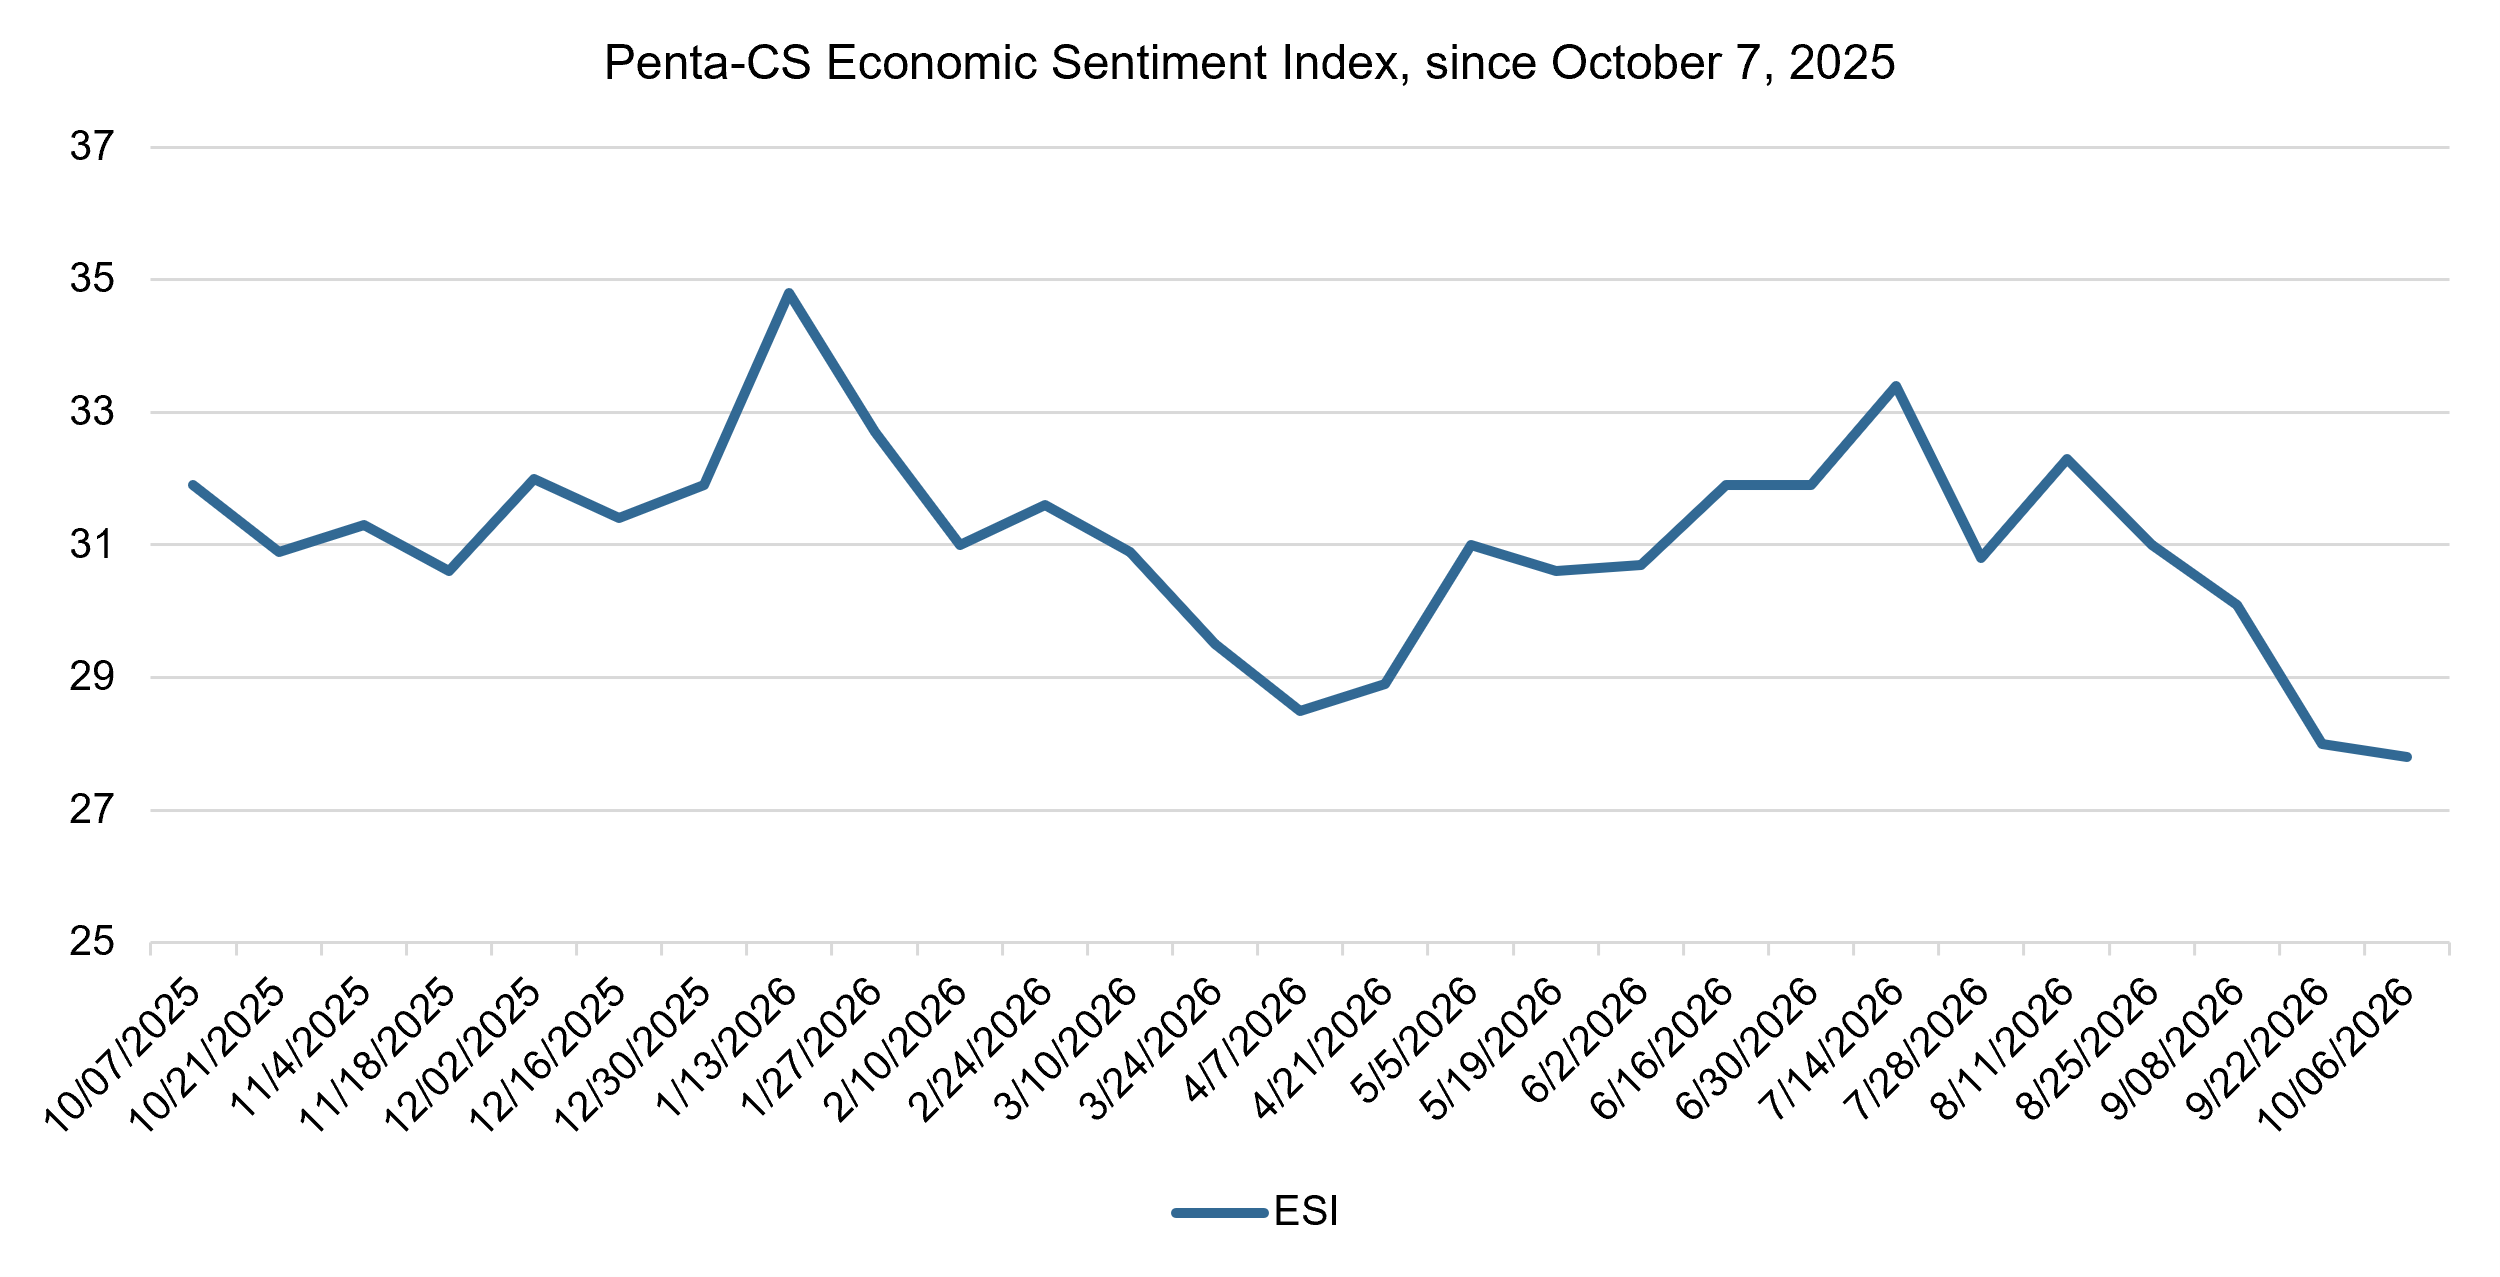
Economic sentiment continued to weaken as the latest biweekly reading of the Penta-CivicScience Economic Sentiment Index (ESI) fell 0.2 points to 27.8, its fourth straight biweekly decline and a new record low.

Click to view image.

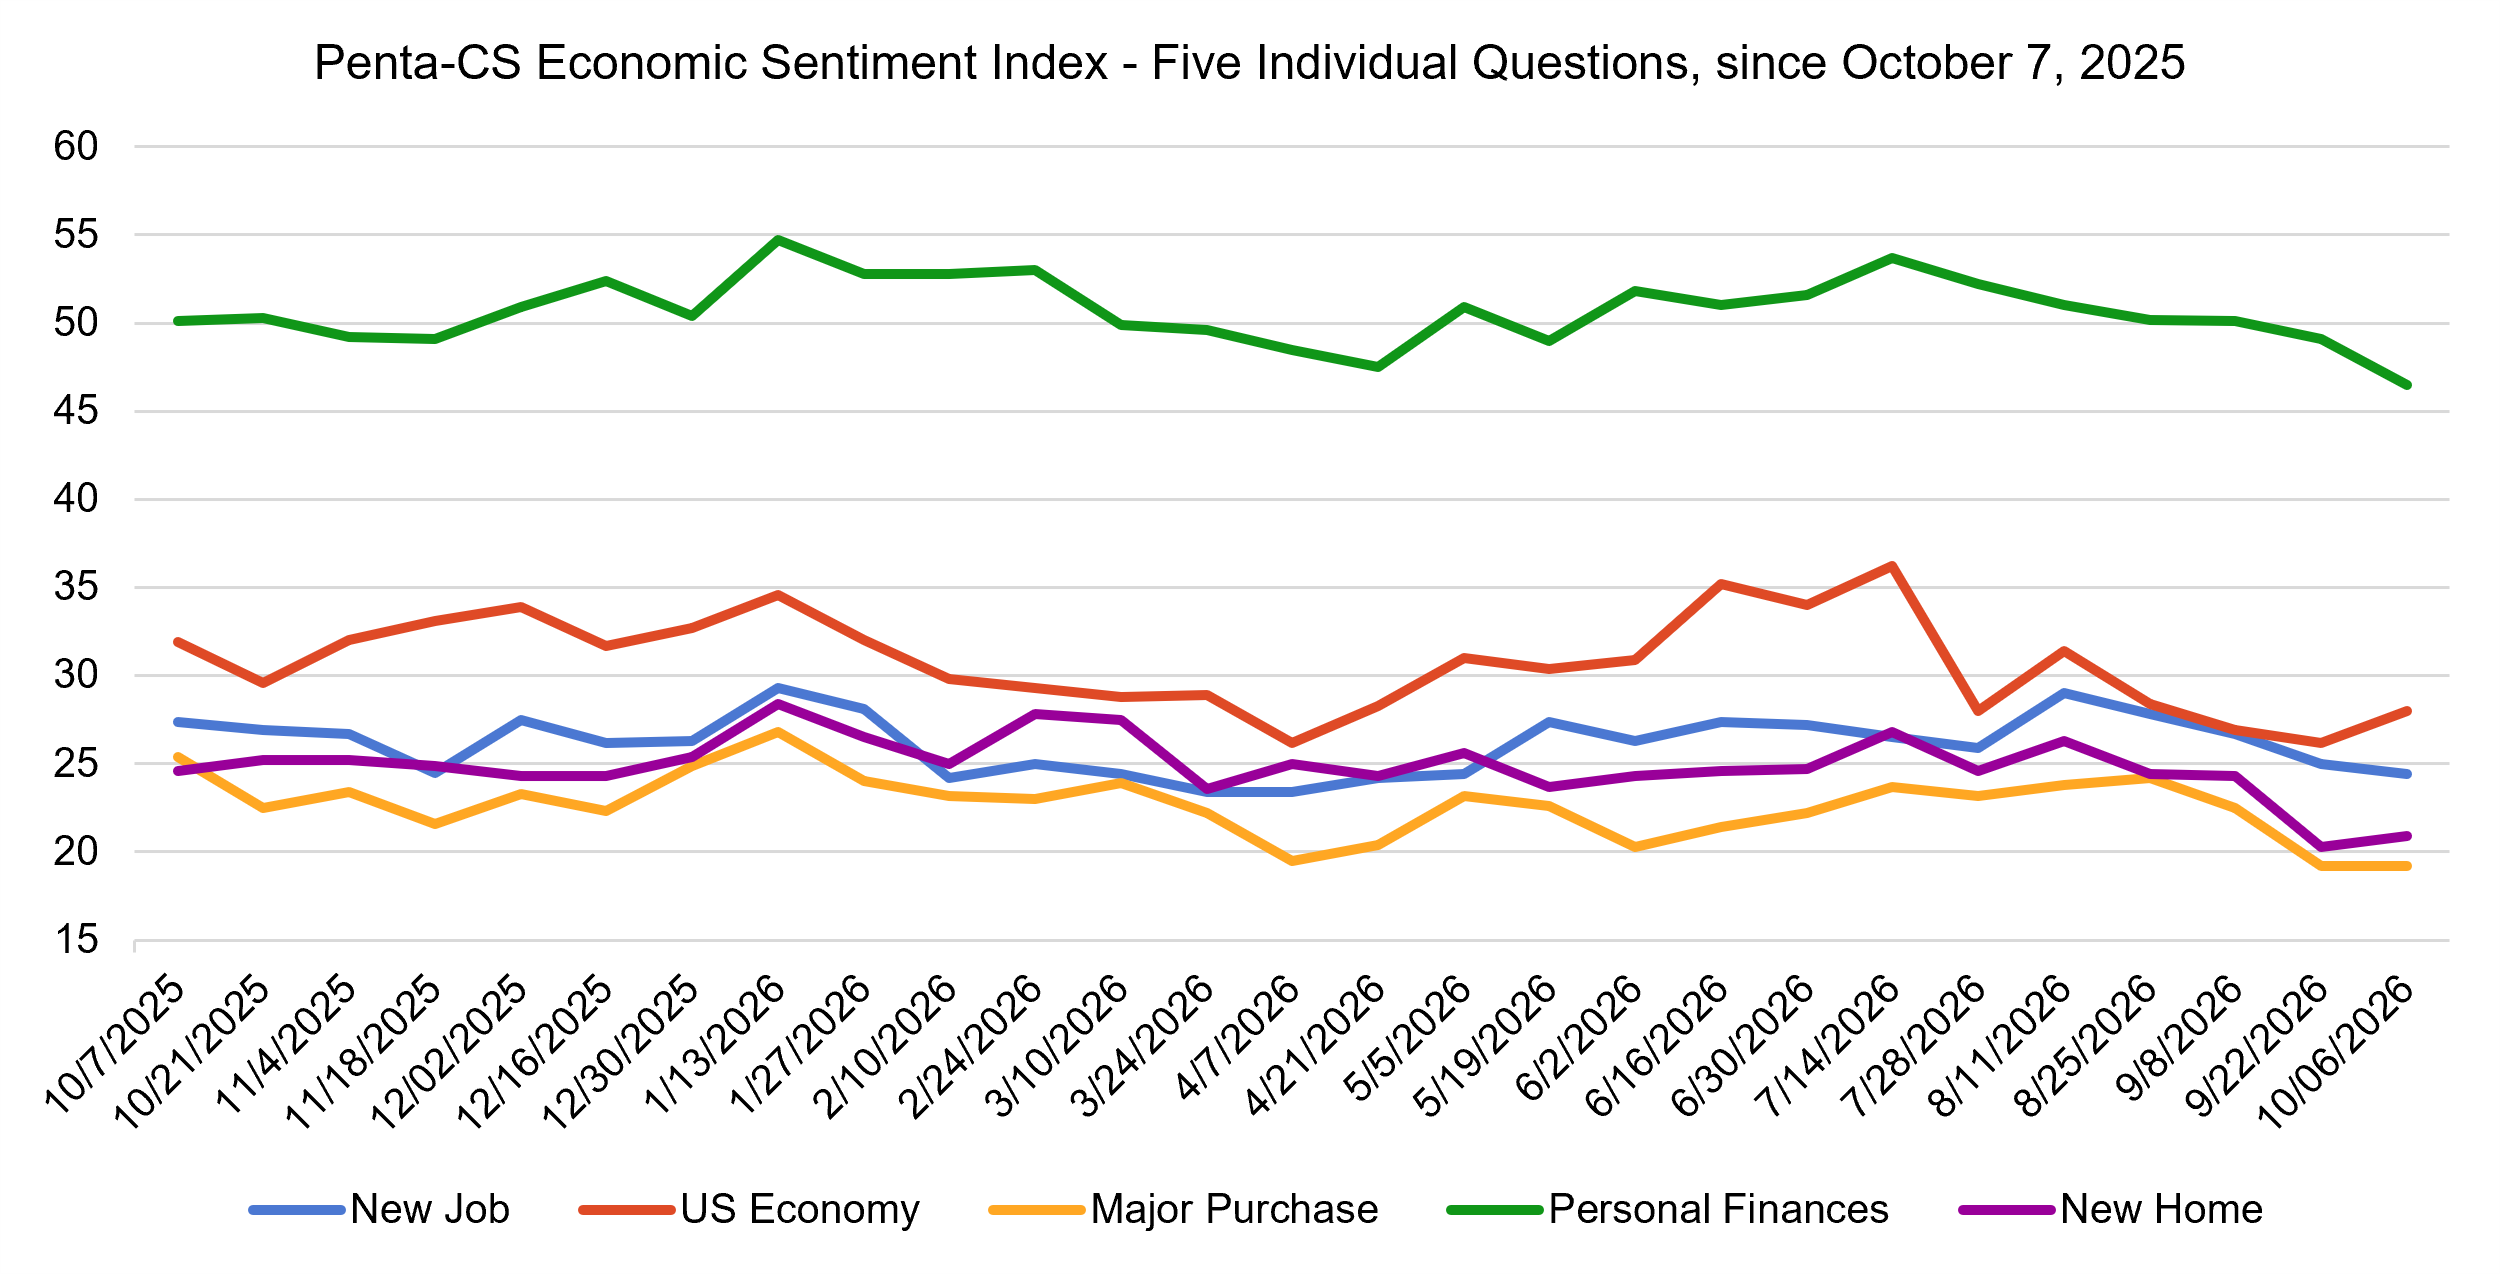
Two of the ESI’s five indicators decreased during this period. Confidence in personal finances decreased the most, falling 2.6 points to 46.5.

—Confidence in finding a new job decreased 0.6 points to 24.4.

—Confidence in making a major purchase remained unchanged at 19.2.

—Confidence in buying a new home increased 0.6 points to 20.9.

—Confidence in the overall U.S. economy increased 1.8 points to 28.0.

Click to view image.

Mortgage rates continued to increase during the period, adding to affordability challenges for prospective homebuyers. Freddie Mac reported that the average 30-year fixed mortgage rate rose to 7.28 percent during the week ending October 1, its highest level since November 2023 and up from 6.34 percent a year earlier. Affordability pressures extended beyond housing, as inflation remained elevated in August. The Bureau of Economic Analysis (BEA) reported that the August Personal Consumption Expenditures (PCE) price index increased 0.3 percent during the month and 3.4 percent year-over-year, remaining above the Federal Reserve’s 2 percent target. Core PCE, which excludes volatile food and energy prices, increased 3.0 percent annually. 

Nevertheless, consumer spending remained resilient despite elevated prices, with personal consumption expenditures increasing 0.9 percent in August. Looking back to earlier in the year, GDP estimates for the second quarter showed stronger growth than previously estimated. BEA reported that real GDP increased at an annual rate of 2.2 percent, up from its previous estimate of 1.5 percent. The revision primarily reflected stronger investment, consumer spending, and government spending than previously estimated. First quarter growth was also revised upward to 2.5 percent from 2.1 percent.

The September Jobs Report showed that U.S. employers added just 29,000 jobs, well below economists’ expectations of 90,000, while the unemployment rate increased slightly to 4.2 percent from 4.1 percent. July and August payroll gains were also revised downward by a combined 60,000 jobs, with July now showing a loss of 10,000 jobs. Financial markets rose following the report as the weaker-than-expected labor market data reduced expectations for another Fed rate increase at its October meeting.

Click to view image.

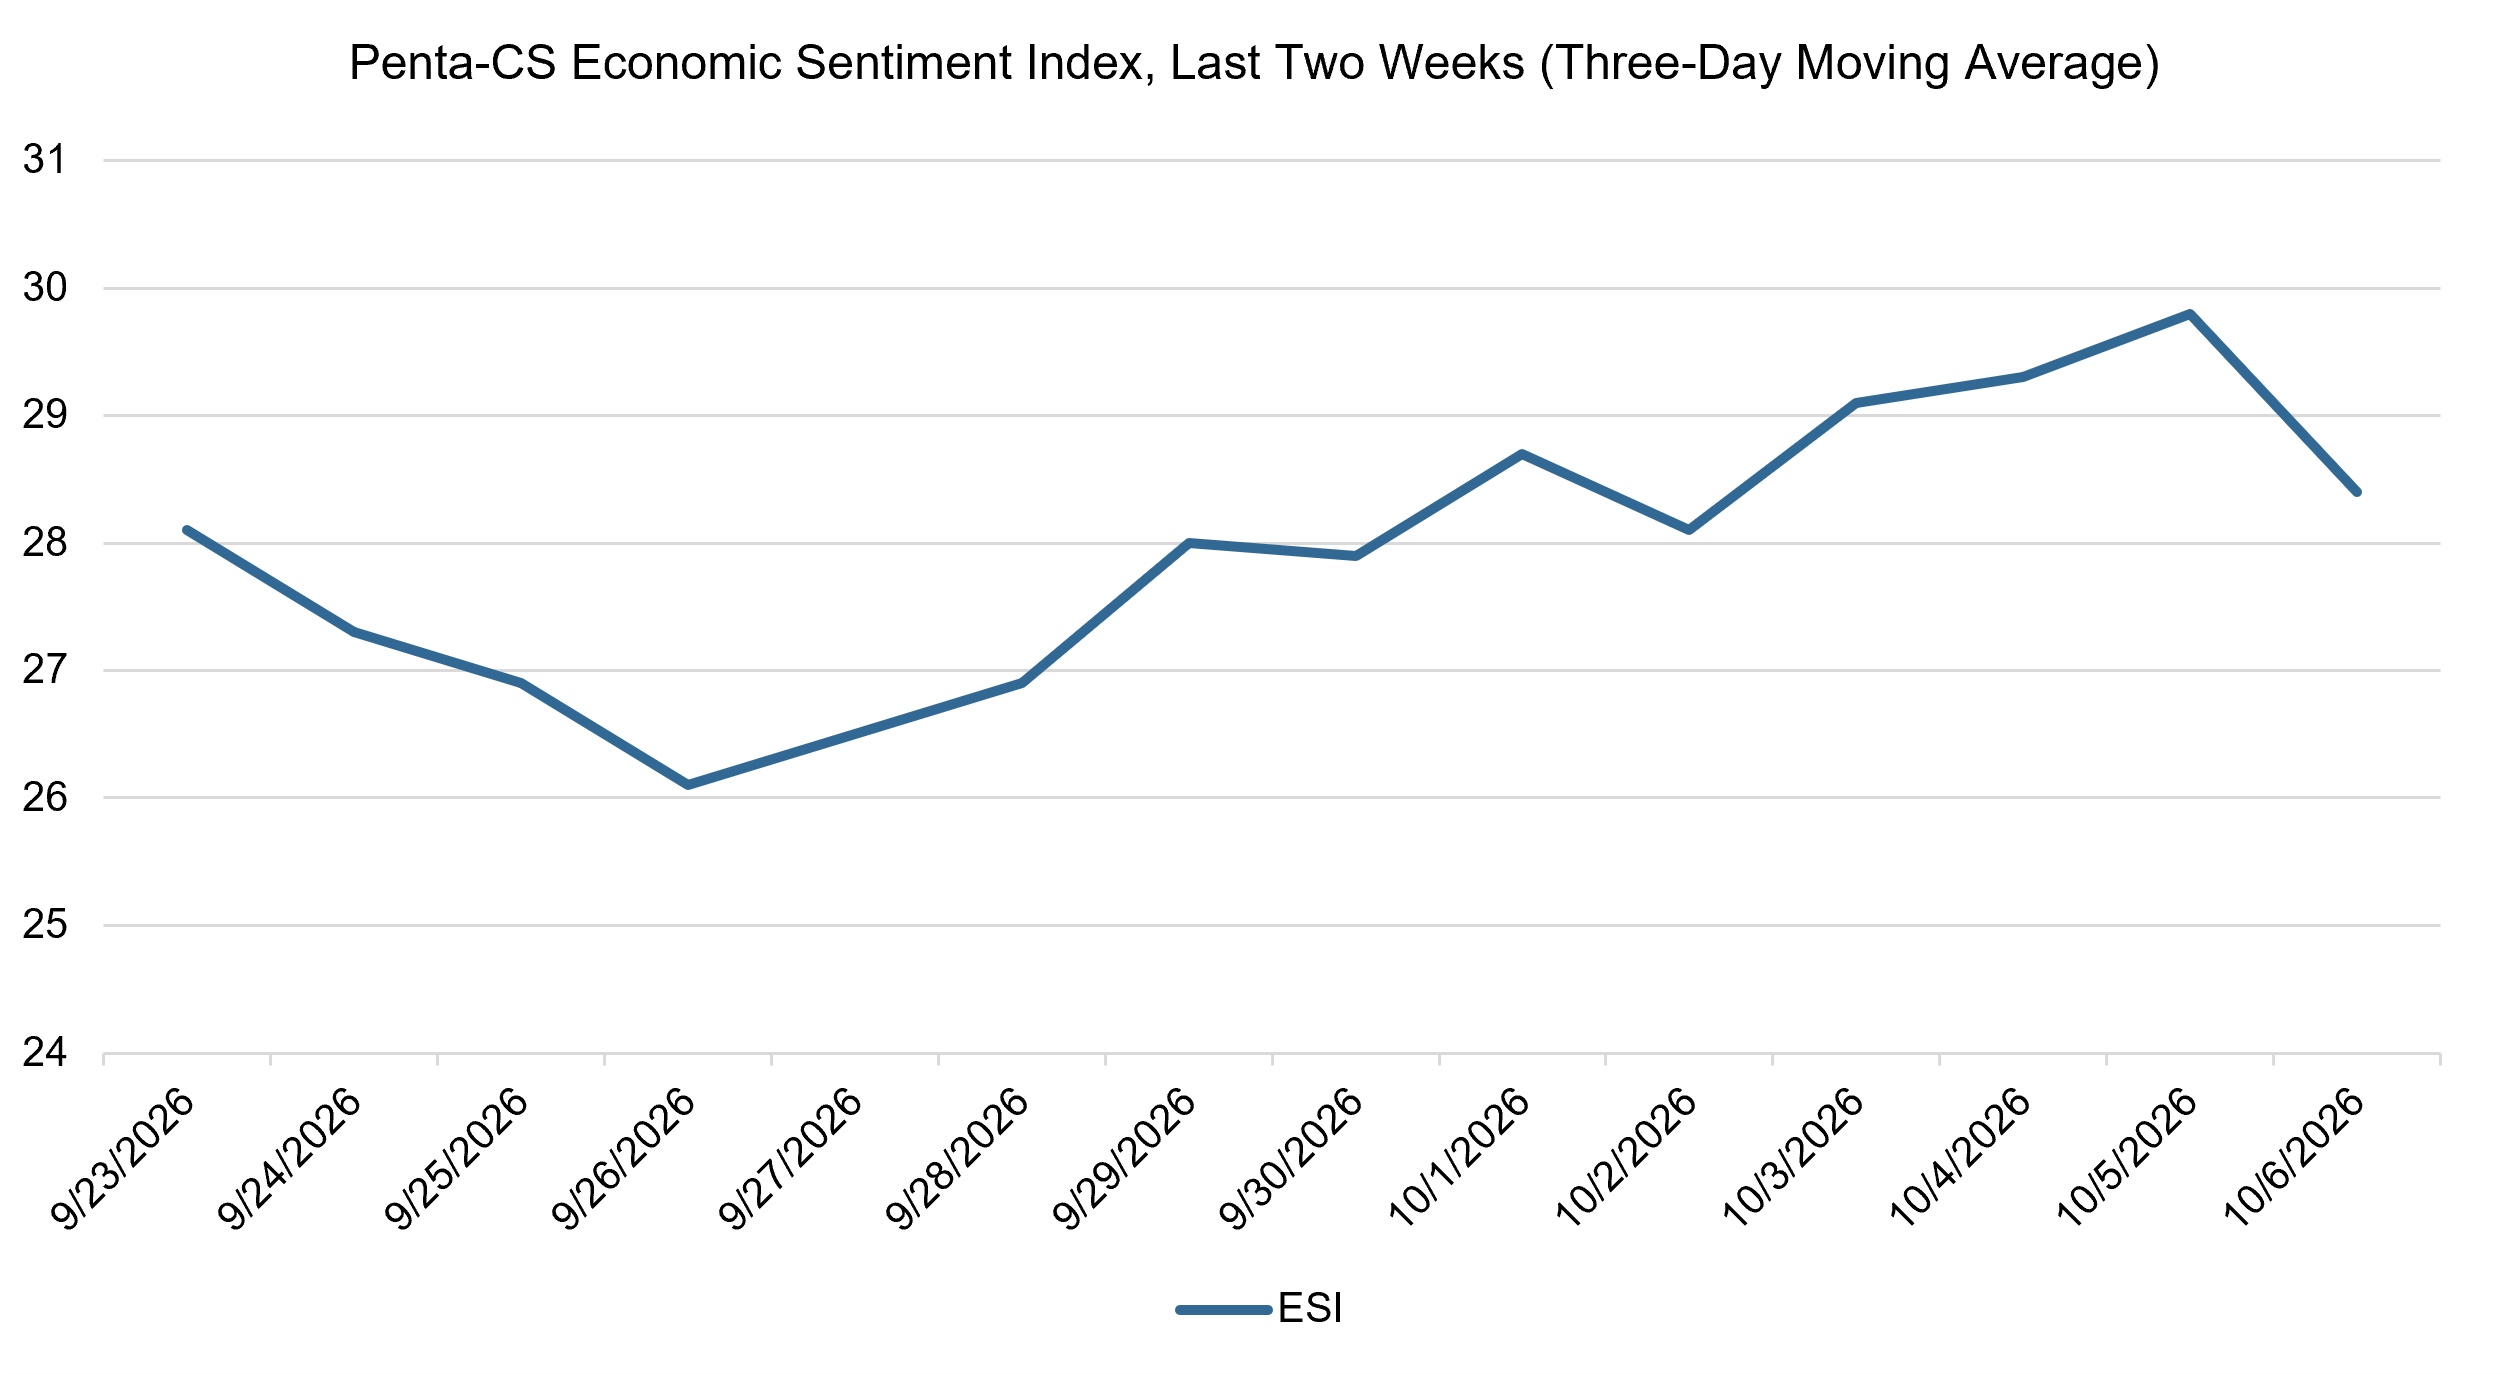
The ESI’s three-day moving average saw two notable declines over the period, separated by a strong rebound that peaked in early October. It began at 28.1 on September 23 before falling to a low of 26.1 on September 26. It then trended upward, rising to a high of 29.8 on October 5 before falling to 28.4 on October 6 to close out the session.

The next release of the ESI will be on Wednesday, October 21, 2026.

Economic sentiment falls to a record low following the Fed’s first rate hike since 2023

The latest biweekly reading of the Penta-CivicScience Economic Sentiment Index (ESI) decreased 2.1 points to 28.0, its lowest level since the index began in 2013, as the Federal Reserve raised interest rates, mortgage rates climbed, and oil prices remained elevated.

Click to view image.

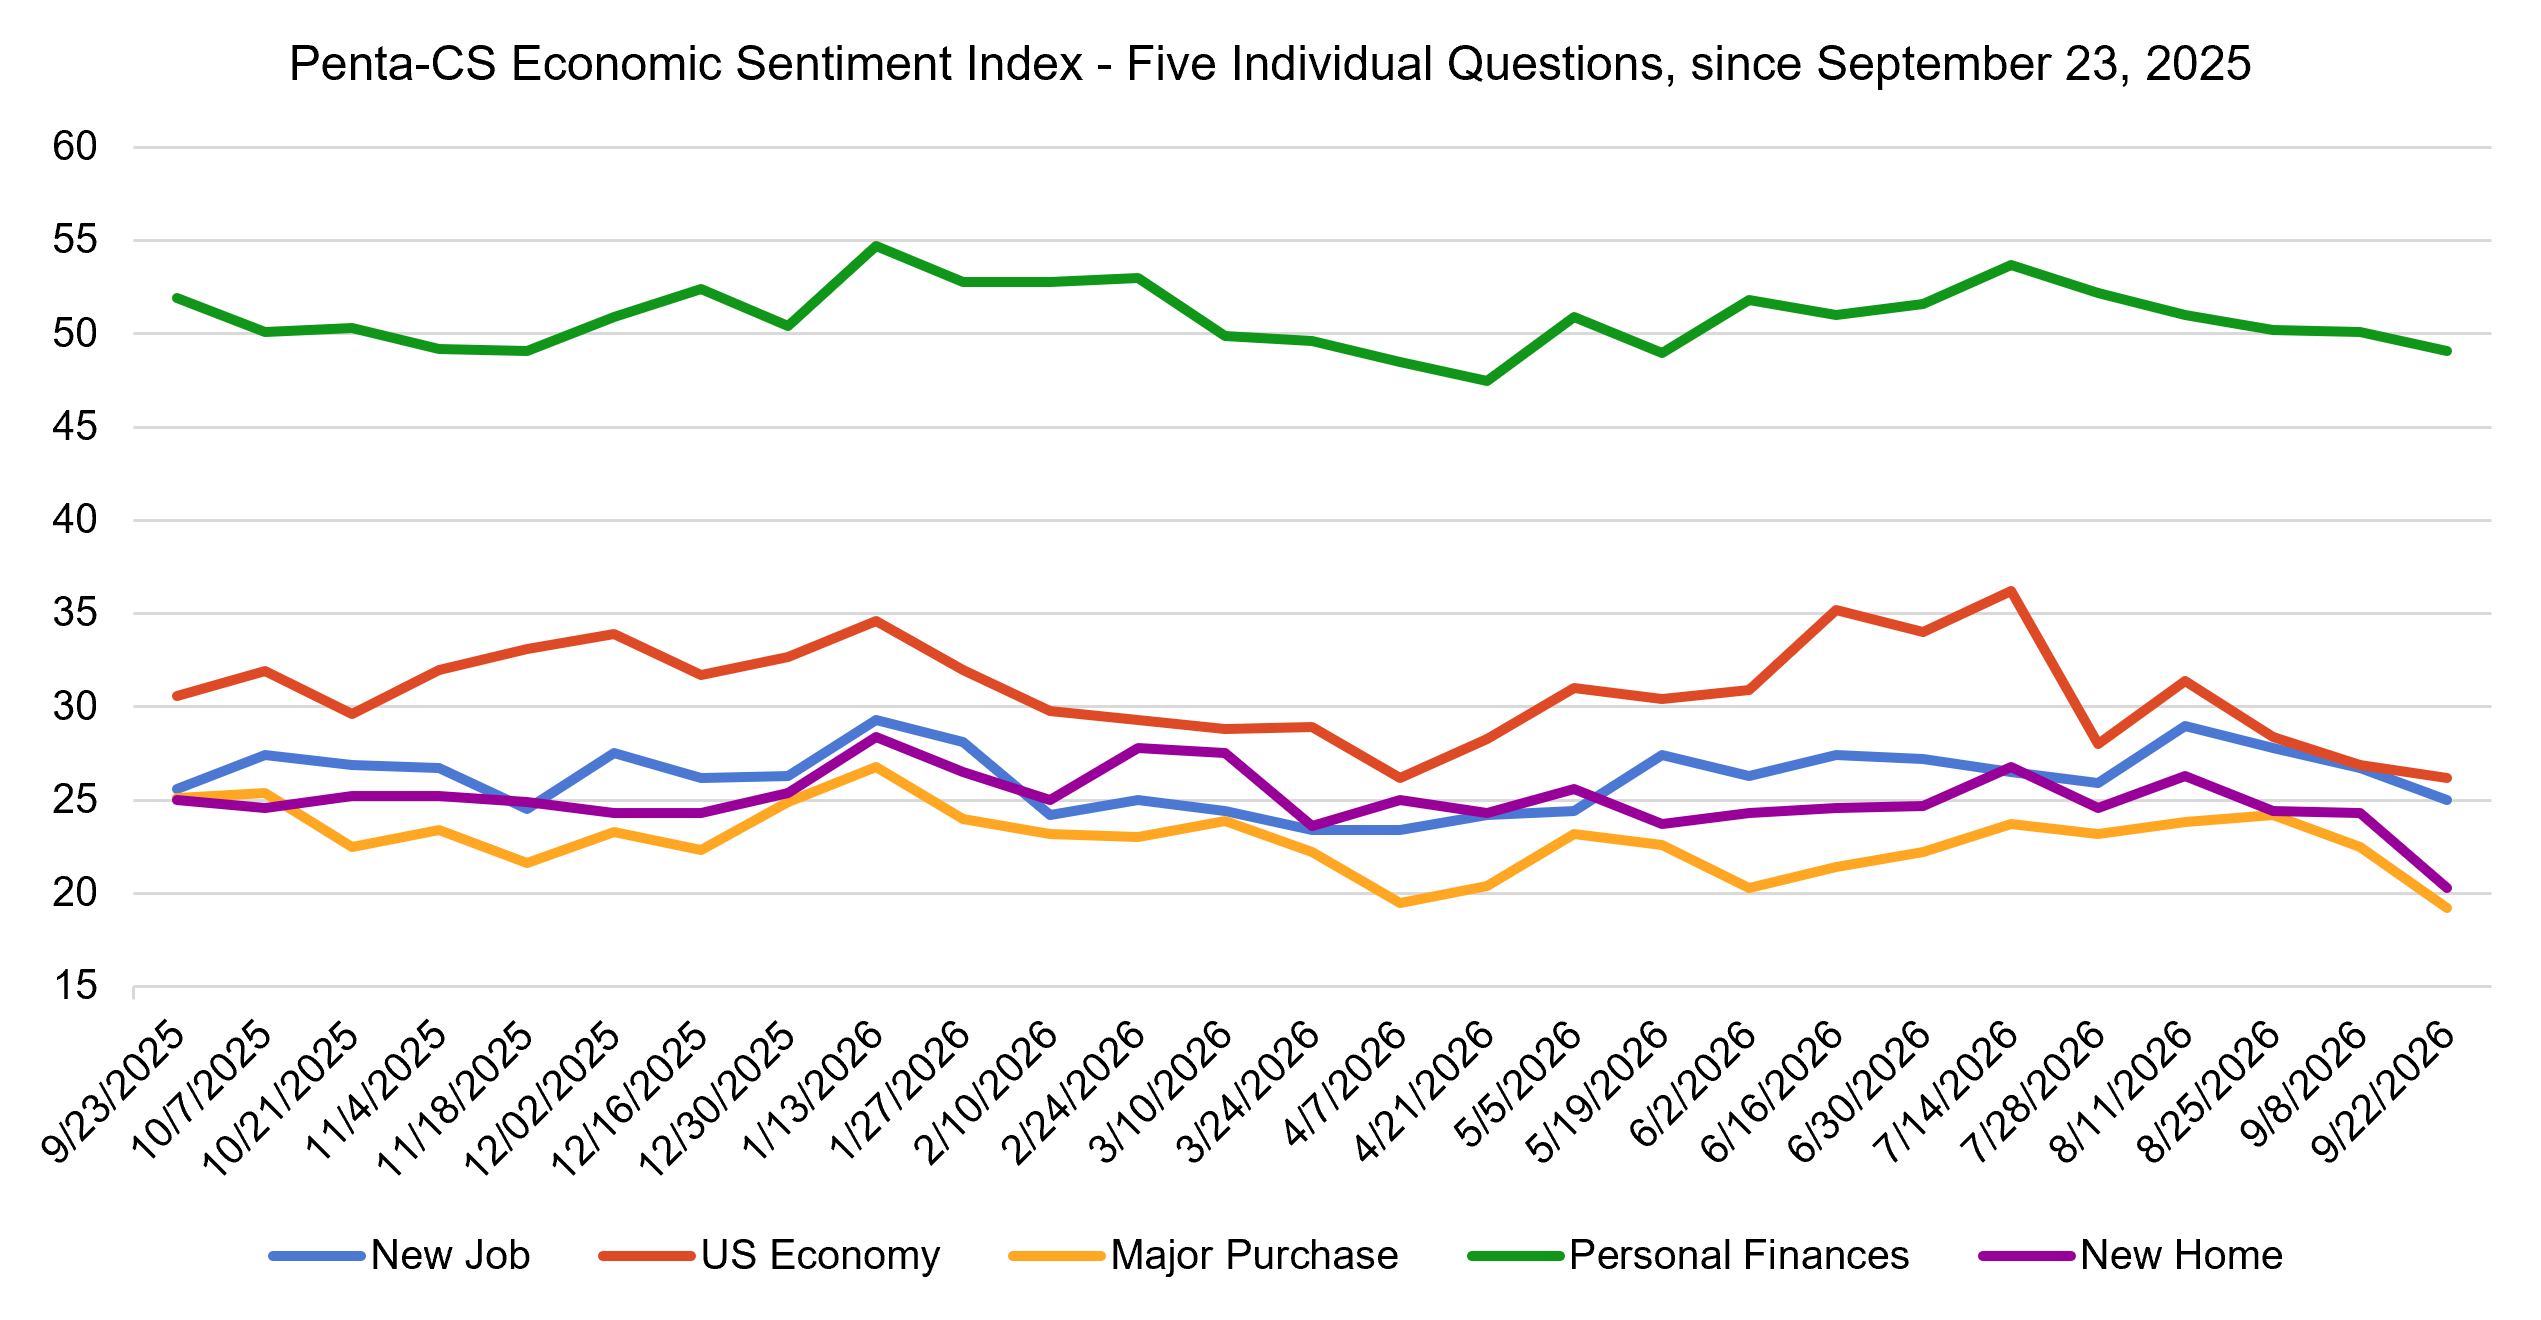
All of the ESI’s five indicators decreased during this period. Confidence in buying a new home decreased the most, falling 4.0 points to 20.3.

—Confidence in making a major purchase decreased 3.3 points to 19.2.
—Confidence in finding a new job decreased 1.7 points to 25.0.
—Confidence in personal finances decreased 1.0 point to 49.1.
—Confidence in the overall U.S. economy decreased 0.7 points to 26.2.

Click to view image.

On September 16, the Federal Open Market Committee (FOMC) voted unanimously to raise the target range for the federal funds rate by a quarter percentage point, to 3.75–4 percent. The increase was the Fed’s first since July 2023. The committee said that inflation remains elevated and that the hike would support a timelier return to its 2 percent goal. Projections released the same day showed 16 of 18 participants expecting another increase this year. This excludes Fed Chair Kevin Warsh, who has declined to submit a projection of his own since taking the role.

Inflation data earlier in the period underscored the challenge facing the Fed. The Bureau of Labor Statistics (BLS) reported that the August Consumer Price Index (CPI) increased 3.4 percent year-over-year, while core CPI, which excludes volatile food and energy prices, rose 2.4 percent. Gasoline prices, which were 27.4 percent higher than a year earlier, accounted for more than a third of the monthly increase. The Producer Price Index (PPI) also rose 5.4 percent over the same period, led by energy prices, which were 24.4 percent higher than a year earlier. Despite this, consumer spending held up in August. The Census Bureau reported that retail and food services sales increased 1.2 percent during the month and 6.0 percent from a year earlier, rebounding from a revised decline in July, though the estimates are not adjusted for inflation and part of the increase reflects higher gasoline prices. 

The bond market also reflected mounting inflation concerns during the period, with the benchmark 10-year Treasury yield briefly touching 5.04 percent on September 15, its highest level since 2007. This came amid a broader global bond selloff as surging oil prices raised fears of renewed inflationary pressure, with the conflict in the Middle East nearing its seventh month. Brent crude climbed to roughly $99 per barrel on September 8 following reports of a second Iranian attack on U.S. Navy ships, and remained near or above $100 for much of the period as disruptions to supply limited exports.

Mortgage rates also increased during the period, adding to affordability challenges for prospective homebuyers. Freddie Mac reported that the average 30-year fixed mortgage rate rose to 6.95 percent during the week ending September 17, its highest level of 2026 and up from 6.76 percent the previous week and 6.26 percent a year earlier. 

Click to view image.

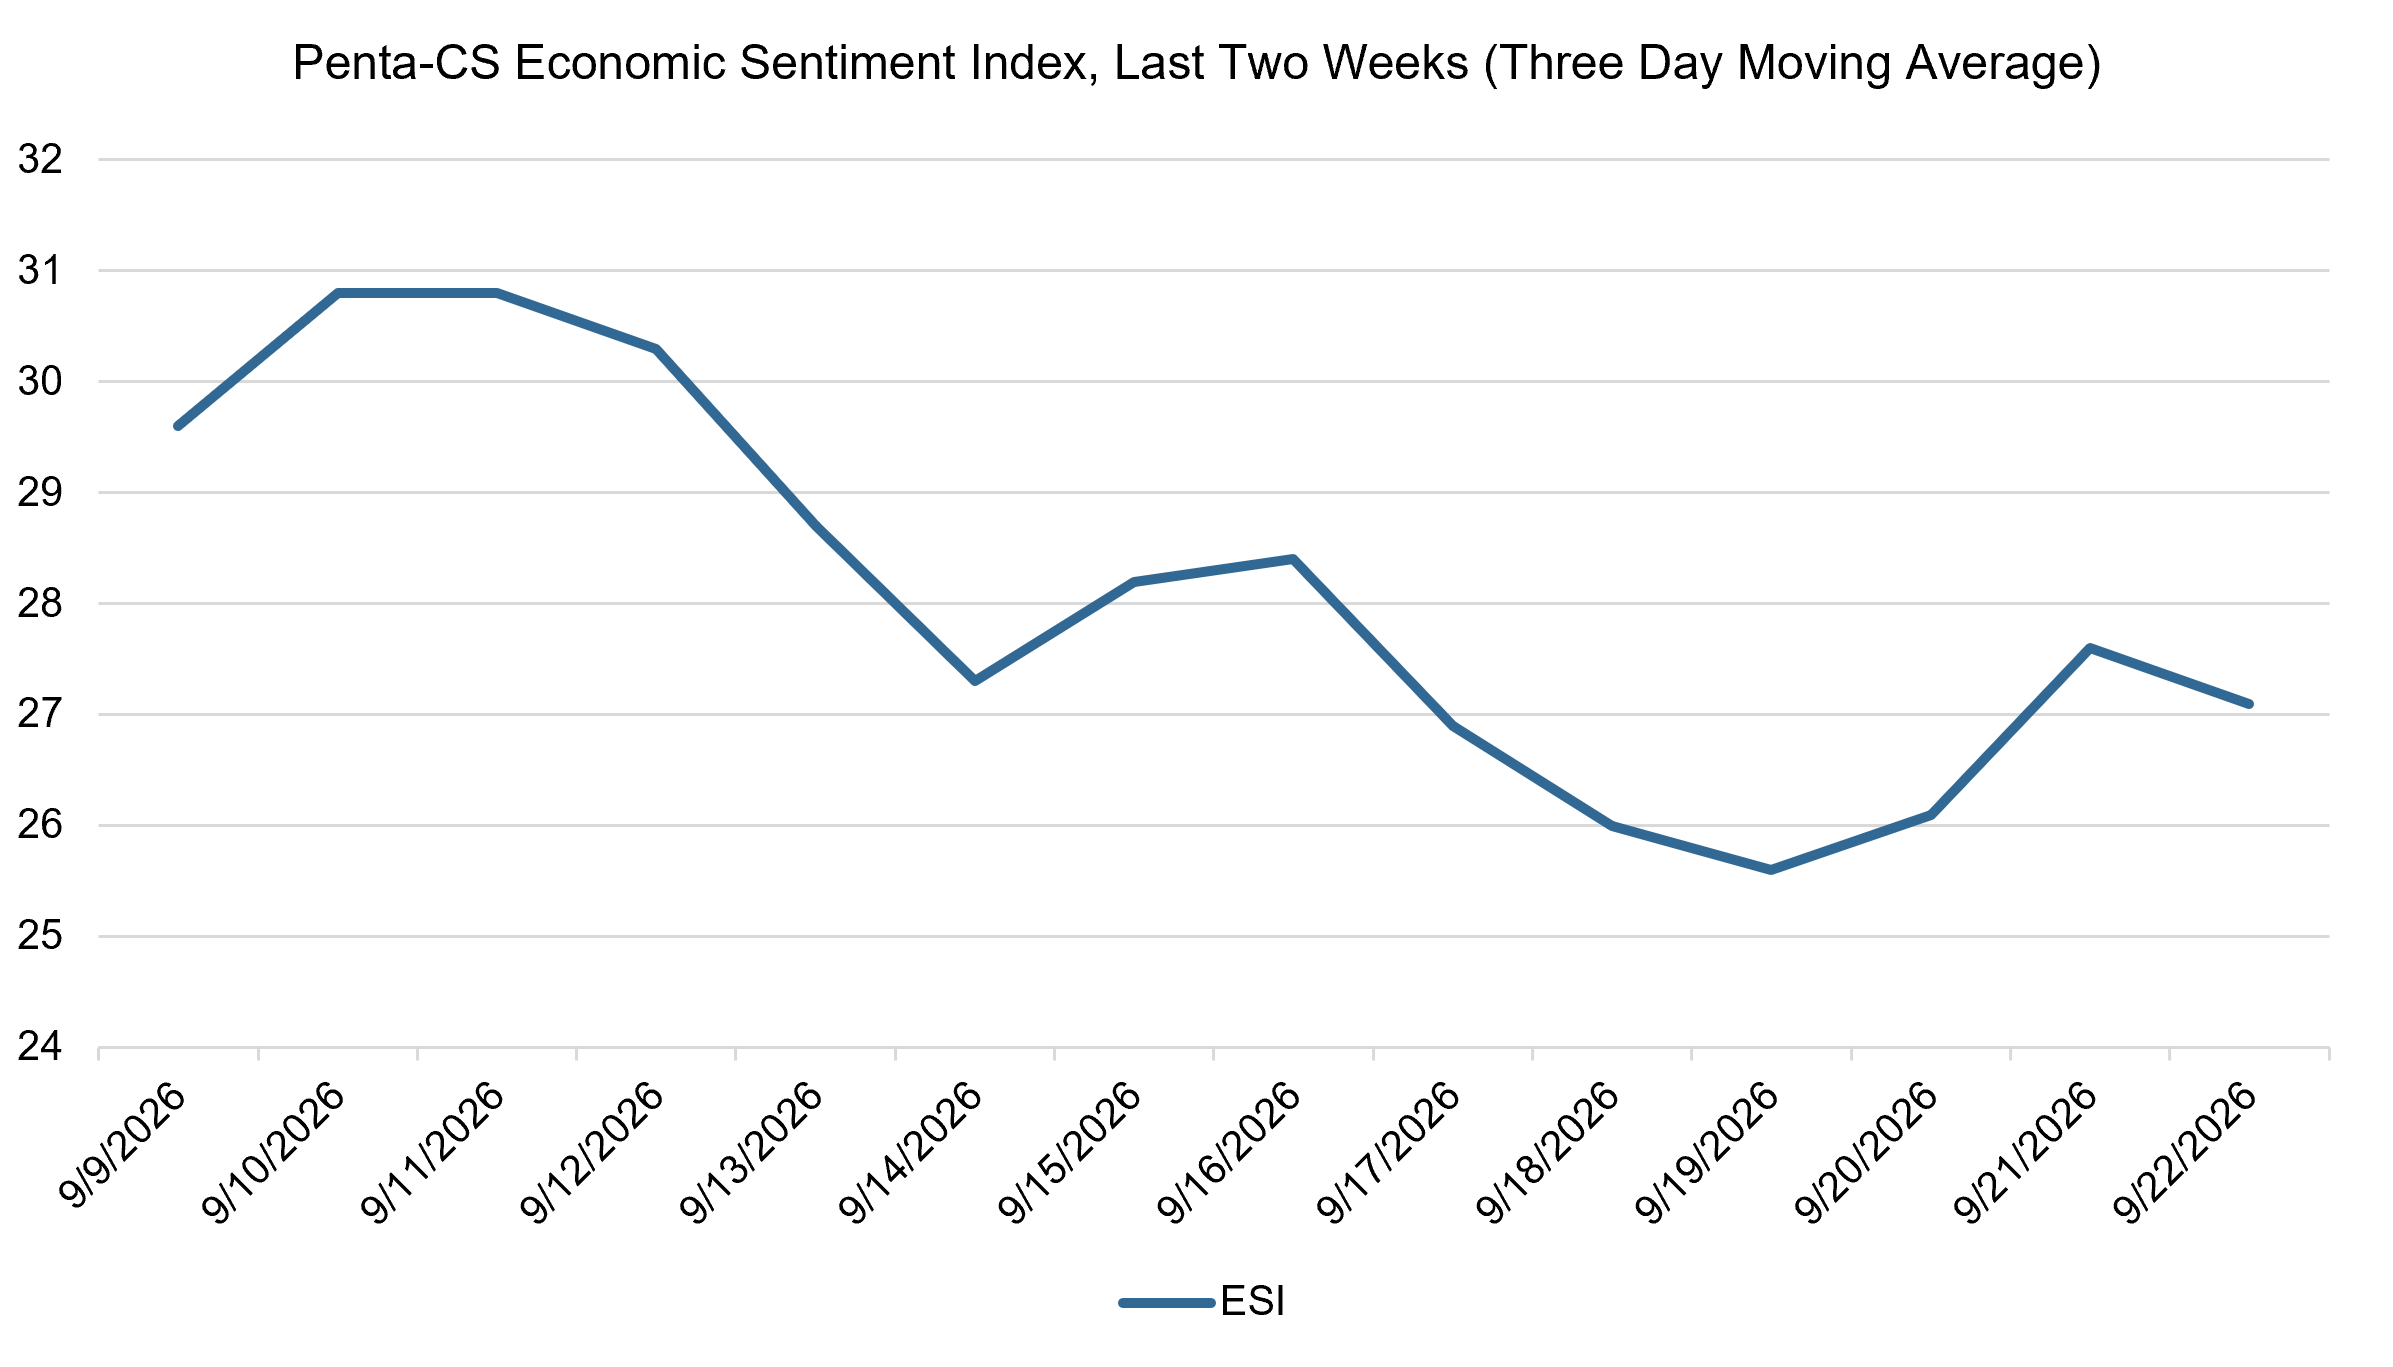
The ESI’s three-day moving average declined overall over the two-week period, despite a late rebound. It began at 29.6 on September 9 before rising to a high of 30.8 on September 10. It then fell, reaching 27.3 on September 14 before briefly recovering to 28.4 on September 16. The three-day moving average then declined to a low of 25.6 on September 19 before climbing to 27.1 on September 22 to close out the session.

The next release of the ESI will be on Wednesday, October 7, 2026.

Note: The previous ESI release on September 9 has been corrected due to a system reporting error affecting the underlying data.

Economic sentiment continues its decline ahead of the September FOMC meeting

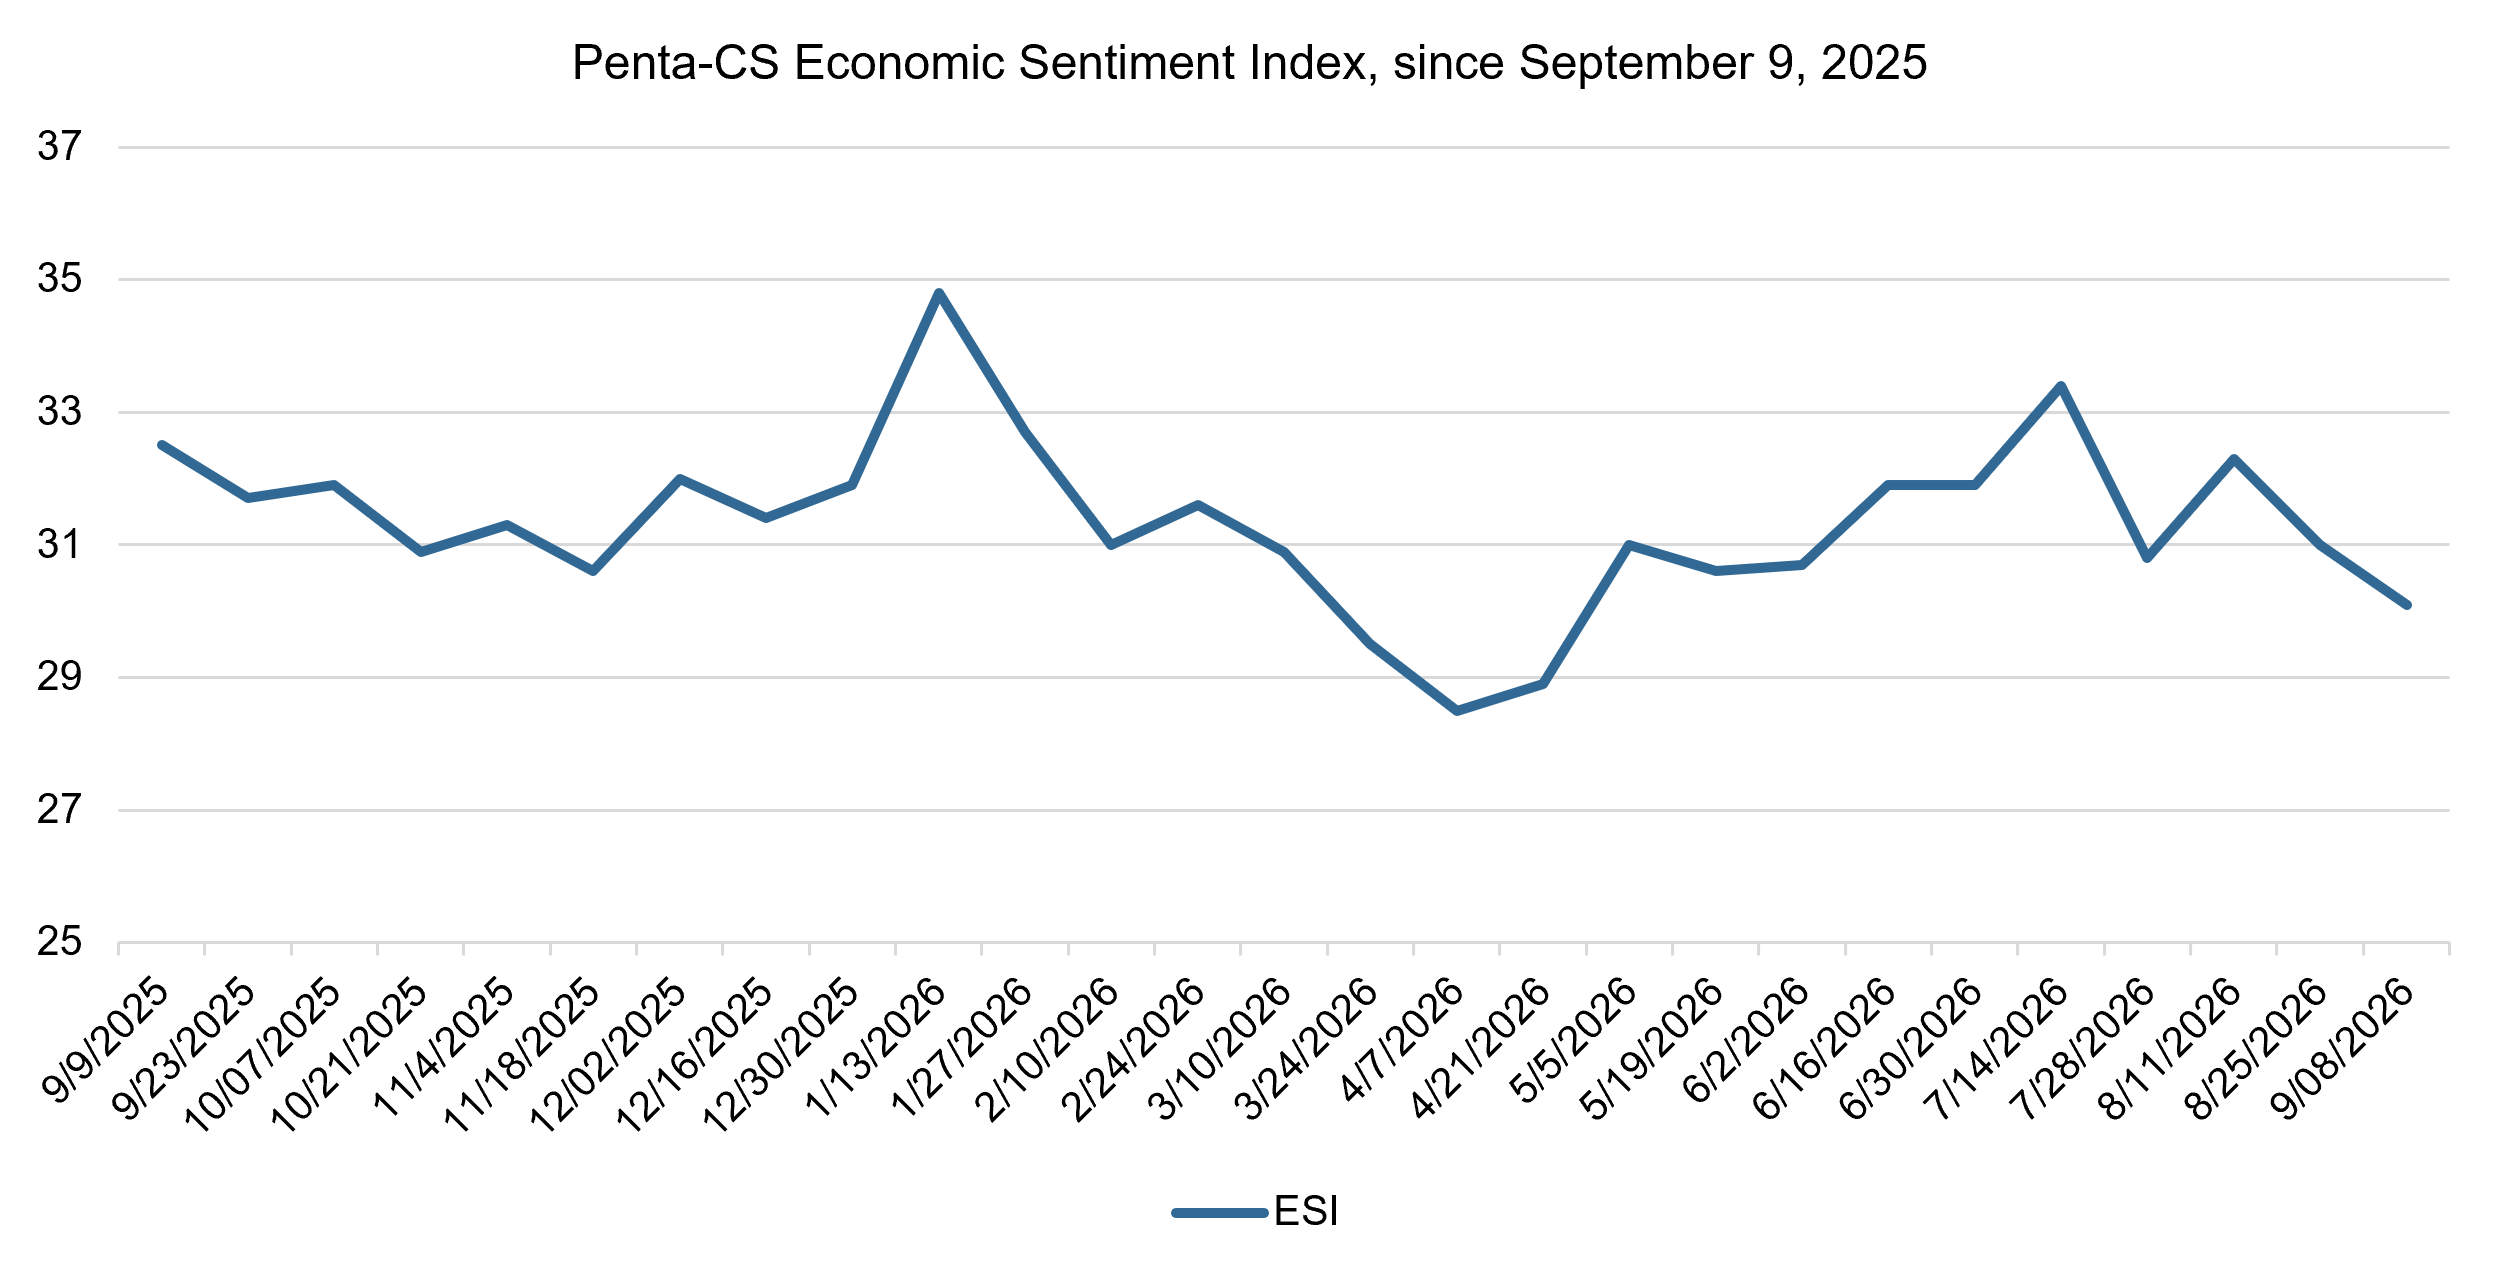
The latest biweekly reading of the Penta-CivicScience Economic Sentiment Index (ESI) decreased 0.9 points to 30.1, as consumers faced persistent inflation, rising borrowing costs, and continued uncertainty in energy markets.

Click to view image

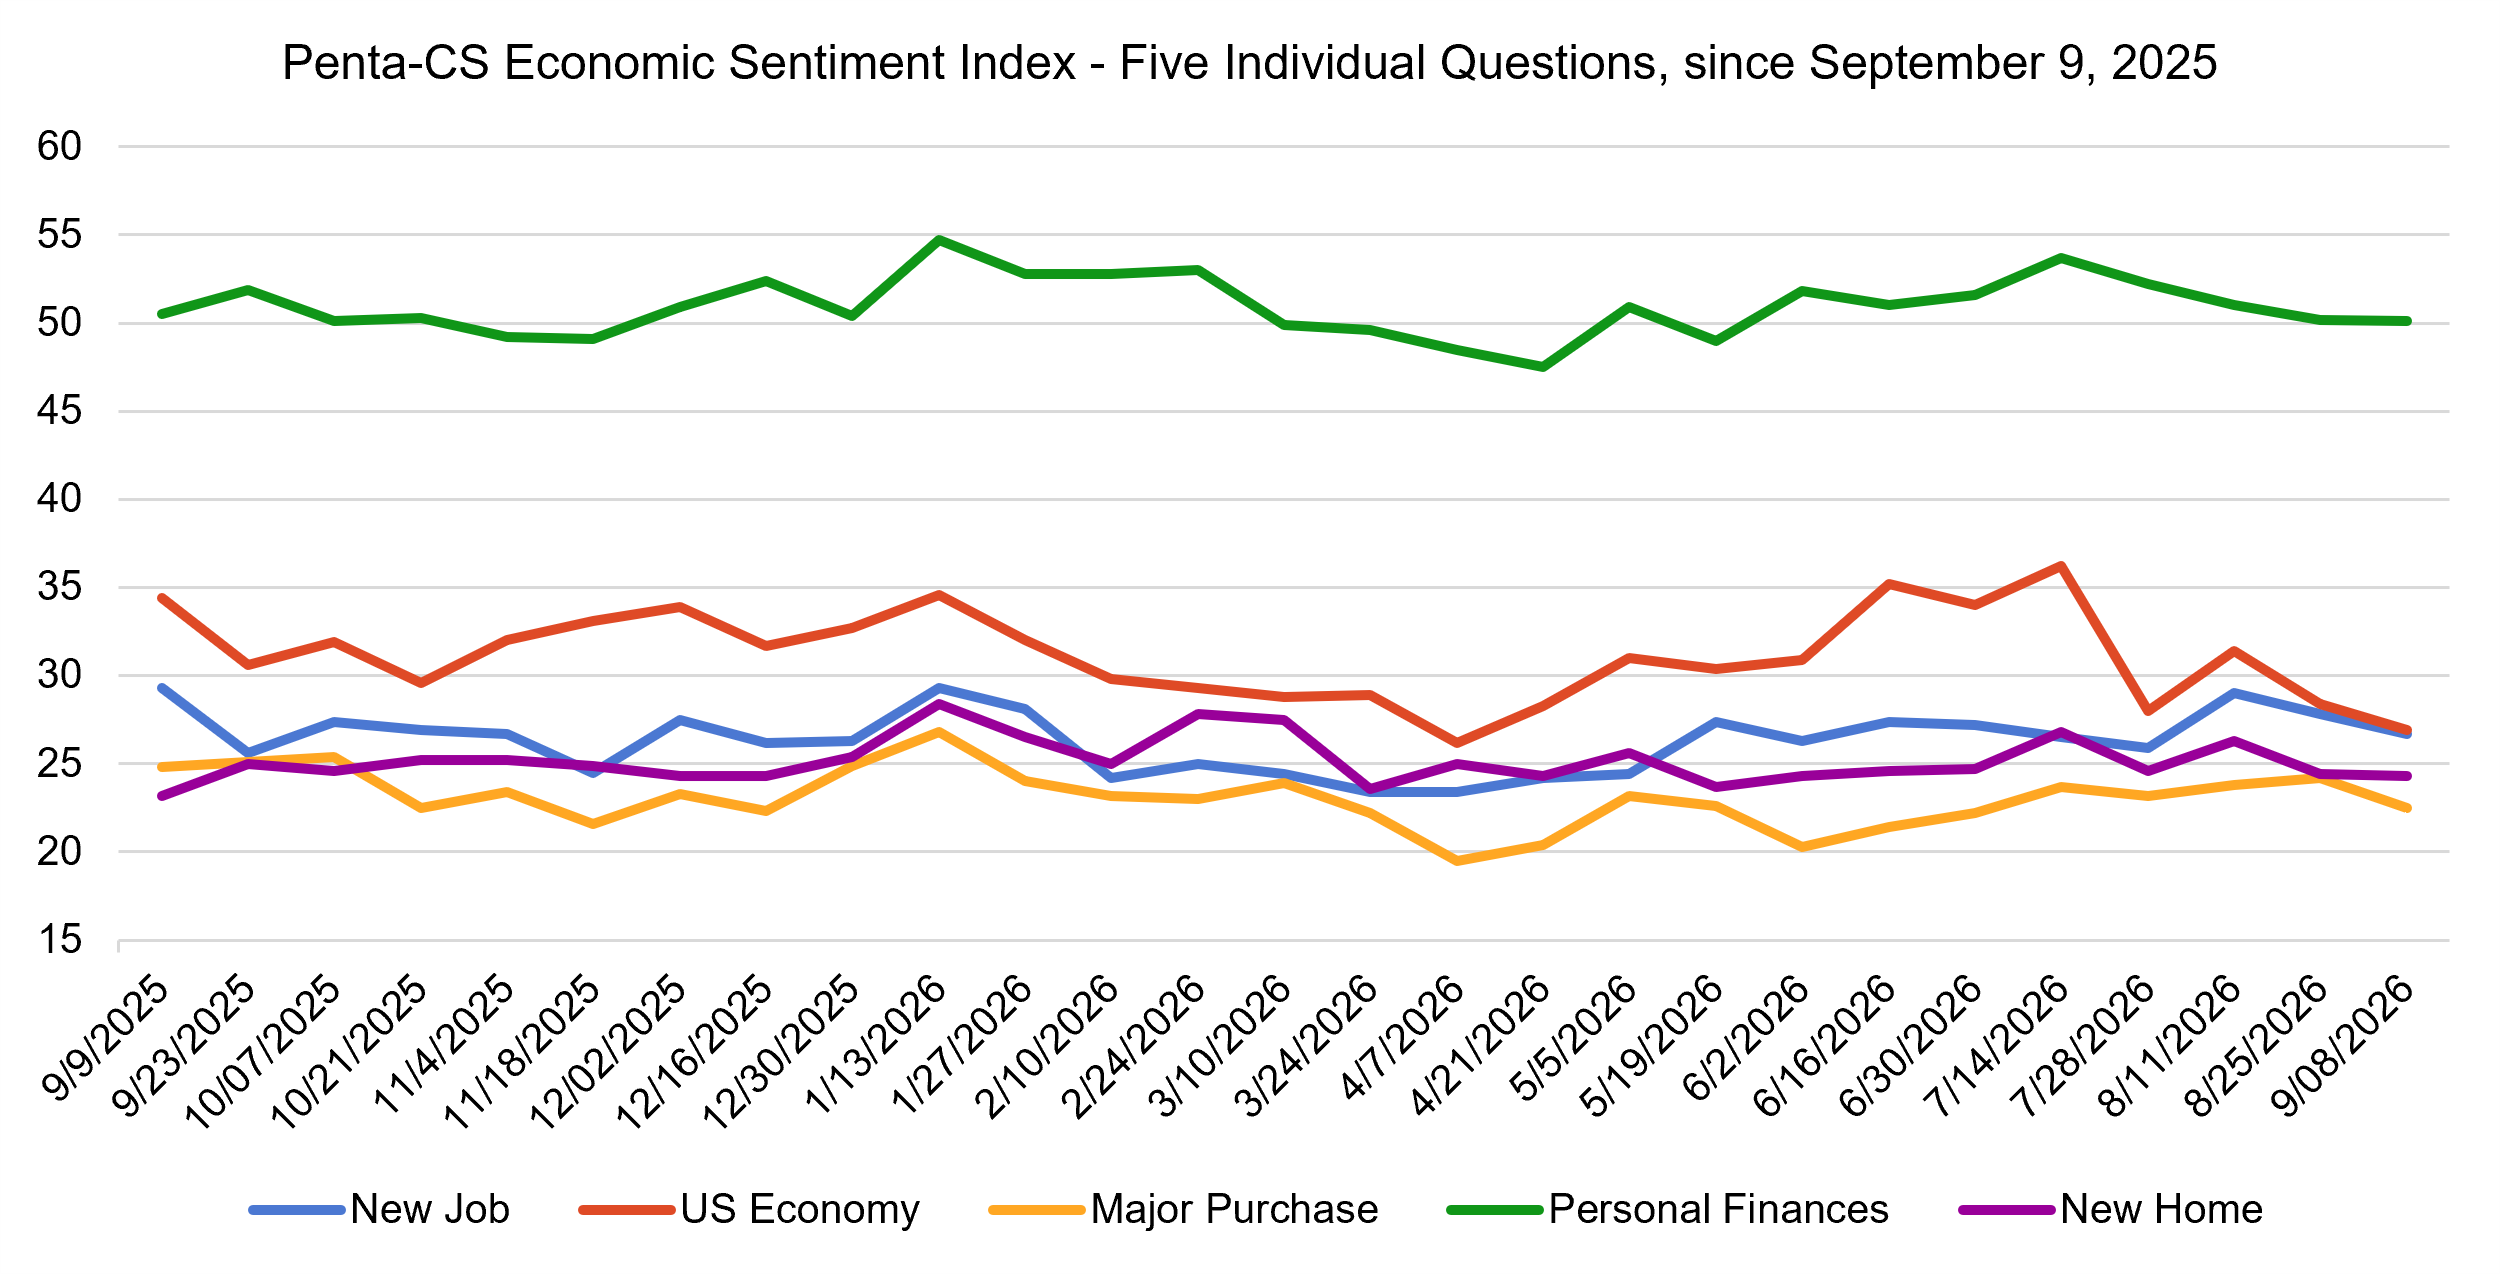
All of the ESI’s five indicators decreased during this period. Confidence in making a major purchase decreased the most, falling 1.7 points to 22.5.

—Confidence in the overall U.S. economy decreased 1.5 points to 26.9.
—Confidence in finding a new job decreased 1.1 points to 26.7.
—Confidence in buying a new home decreased 0.1 points to 24.3.
—Confidence in personal finances decreased 0.1 points to 50.1.

Click to view image

The Bureau of Economic Analysis (BEA) reported that the July Personal Consumption Expenditures (PCE) price index increased 0.2 percent during the month and 3.7 percent year-over-year, remaining above the Federal Reserve’s 2 percent target. Core PCE, which excludes volatile food and energy prices, increased 3.3 percent annually. Meanwhile, consumer spending rose just 0.2 percent and was essentially flat after adjusting for inflation, as elevated prices continued to weigh on consumers.

At the Fed’s annual Jackson Hole symposium, Fed Chair Kevin Warsh reiterated the central bank’s focus on controlling inflation, stating that the Fed’s “predominant focus right now should be on prices.” Subsequent developments in energy markets underscored the challenge facing the Fed. Oil prices rose sharply as continued conflict between the United States and Iran raised concerns about global energy supplies. On September 8, Brent crude approached $100 for the first time since July. A sustained increase in energy prices could place additional pressure on gasoline prices and broader inflation, further complicating the Fed’s interest rate decisions.

The August Jobs Report showed that employers added 162,000 jobs while the unemployment rate remained unchanged at 4.1 percent. The increase significantly exceeded economists’ expectations, while June and July payroll gains were revised upward by a combined 55,000 jobs. Financial markets fell following the report as the stronger-than-expected results increased expectations for a rate hike at the Fed’s September meeting.

Mortgage rates also increased during the period, adding to affordability challenges for prospective homebuyers. Freddie Mac reported that the average 30-year fixed mortgage rate rose to 6.71 percent during the week ending September 3, its highest level of 2026 and up from 6.66 percent the previous week. The increase comes as rising Treasury yields continue to push borrowing costs higher.

Click to view image

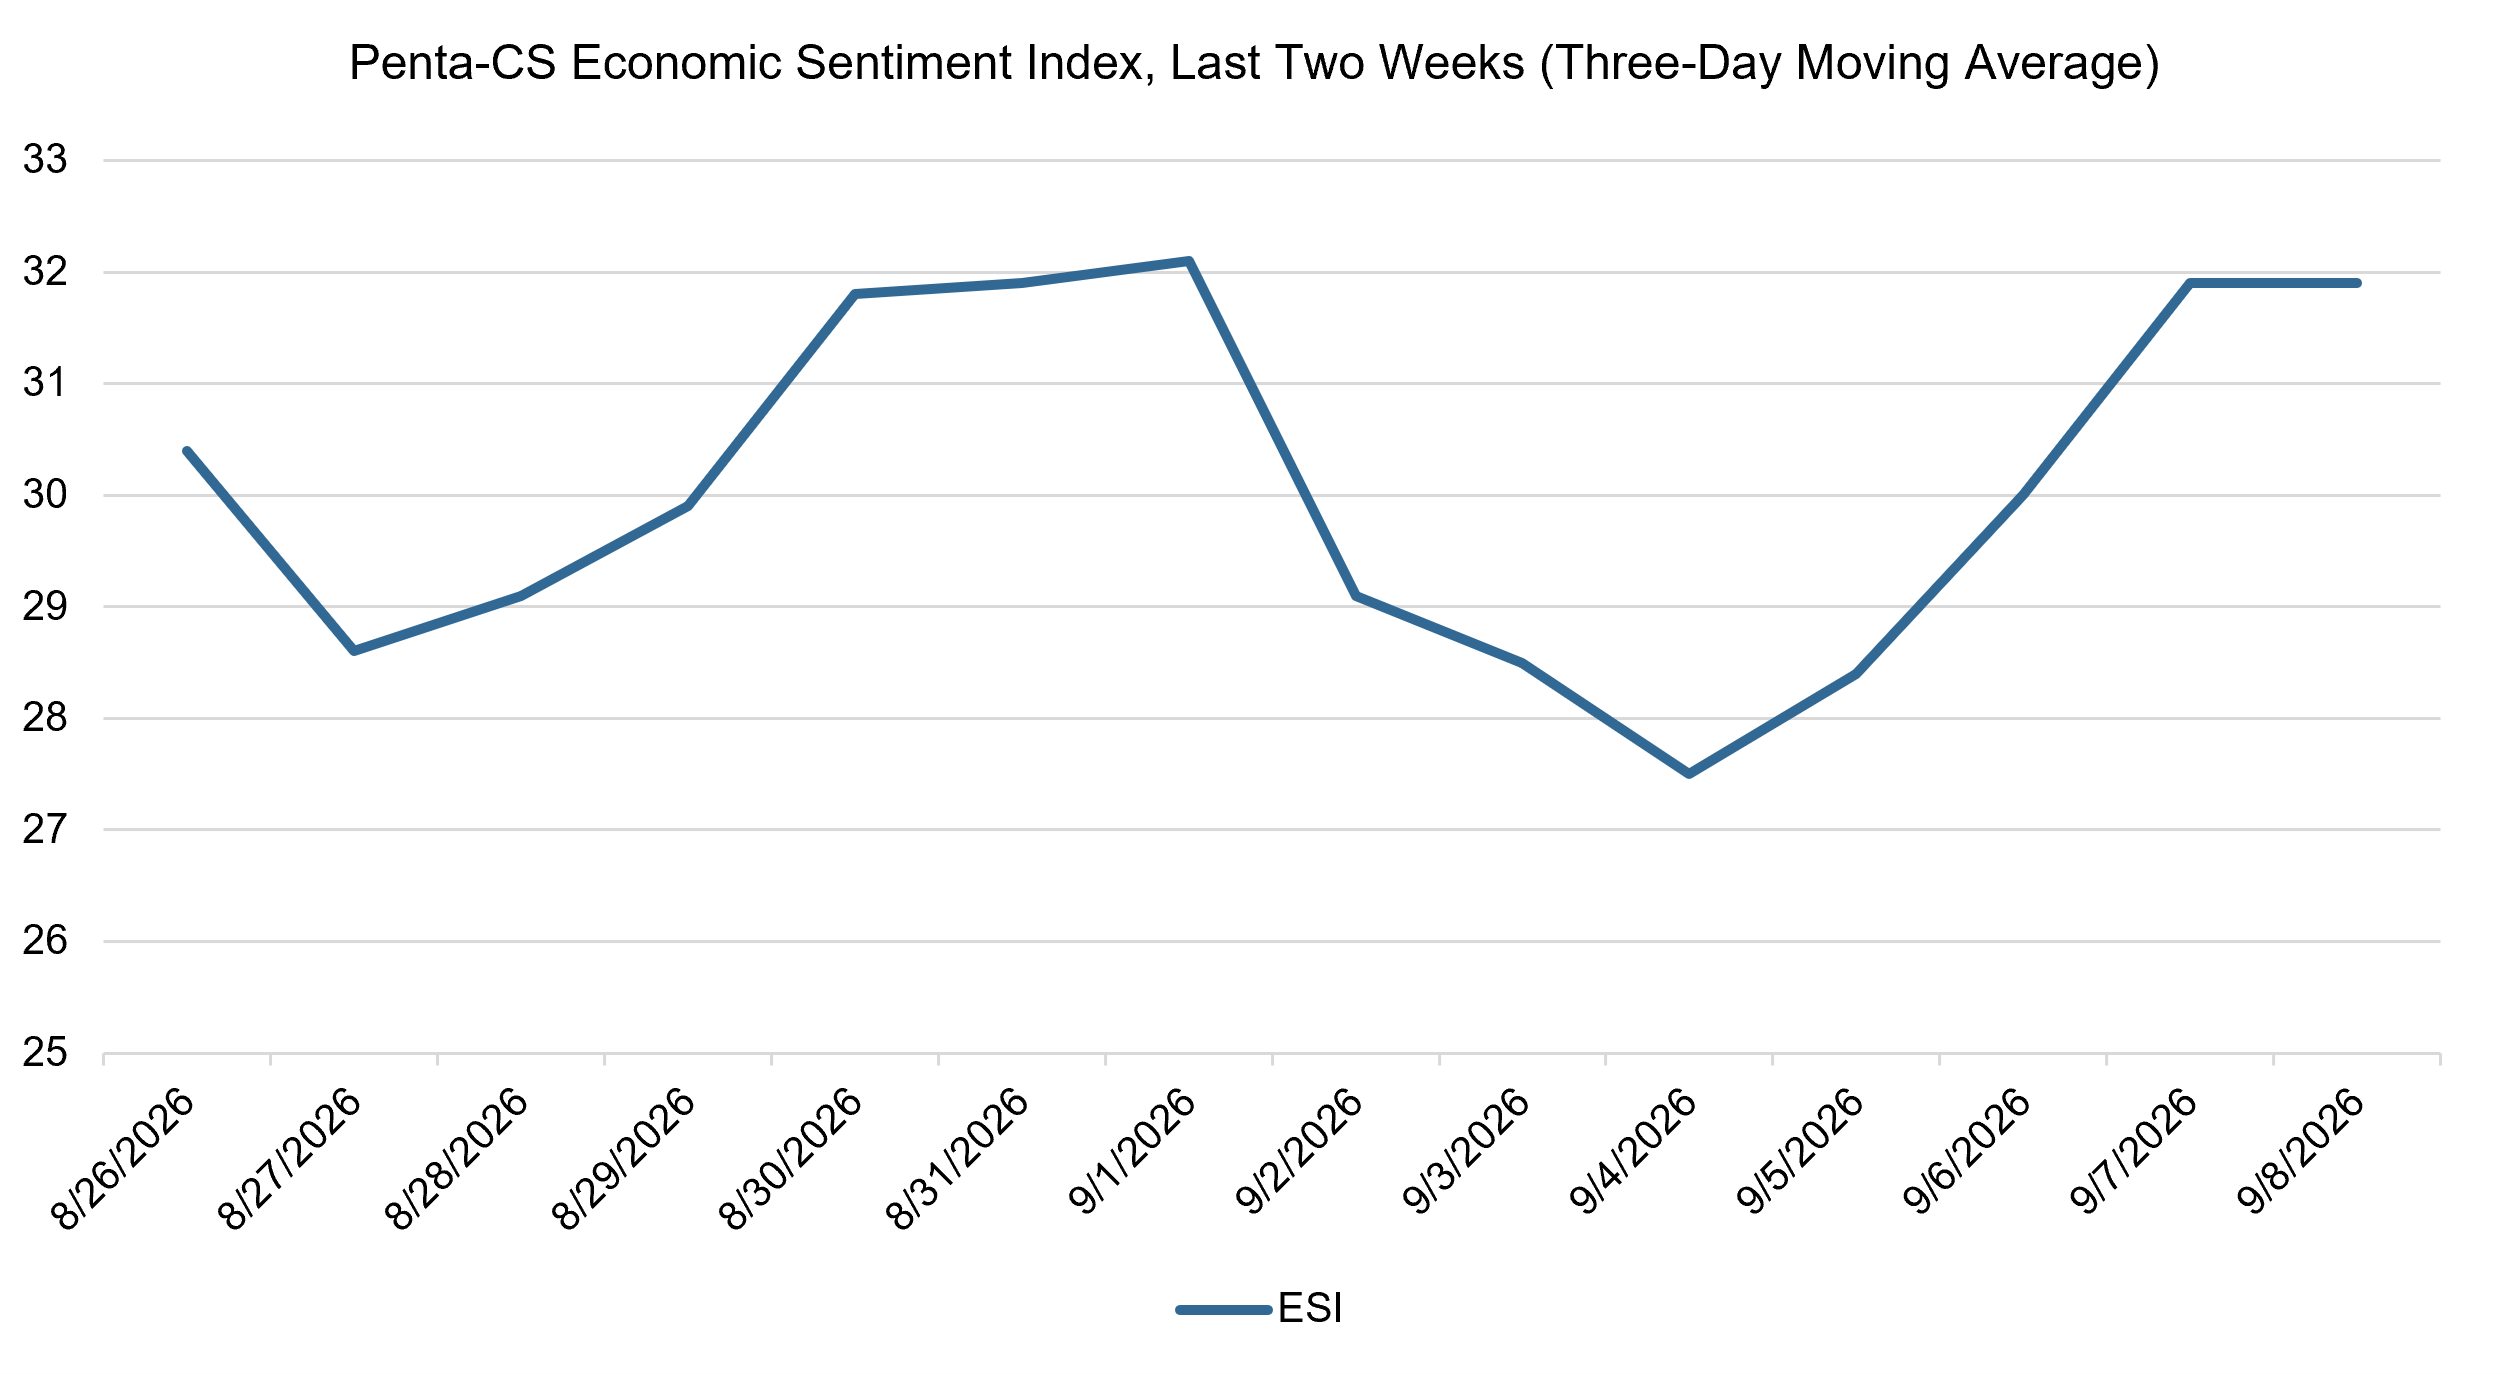
The ESI’s three-day moving average followed a volatile path over the two-week period. It began at 30.4 on August 26 before falling sharply the next day to 28.6. It then rose up, reaching a high of 32.1 on September 1 before plummeting to a low of 27.5 on September 4. The three-day moving average then rose back up, reaching 31.9 on September 8 to close out the session.

The next release of the ESI will be on Wednesday, September 23, 2026.

Note: This article was updated on September 15, 2026. A system reporting error affected the underlying data, requiring an update to the headline, selected body text, and charts. The current version reflects the finalized, audited data for August 26–September 8, 2026.

Economic sentiment declines amid rising bond yields and new tariffs

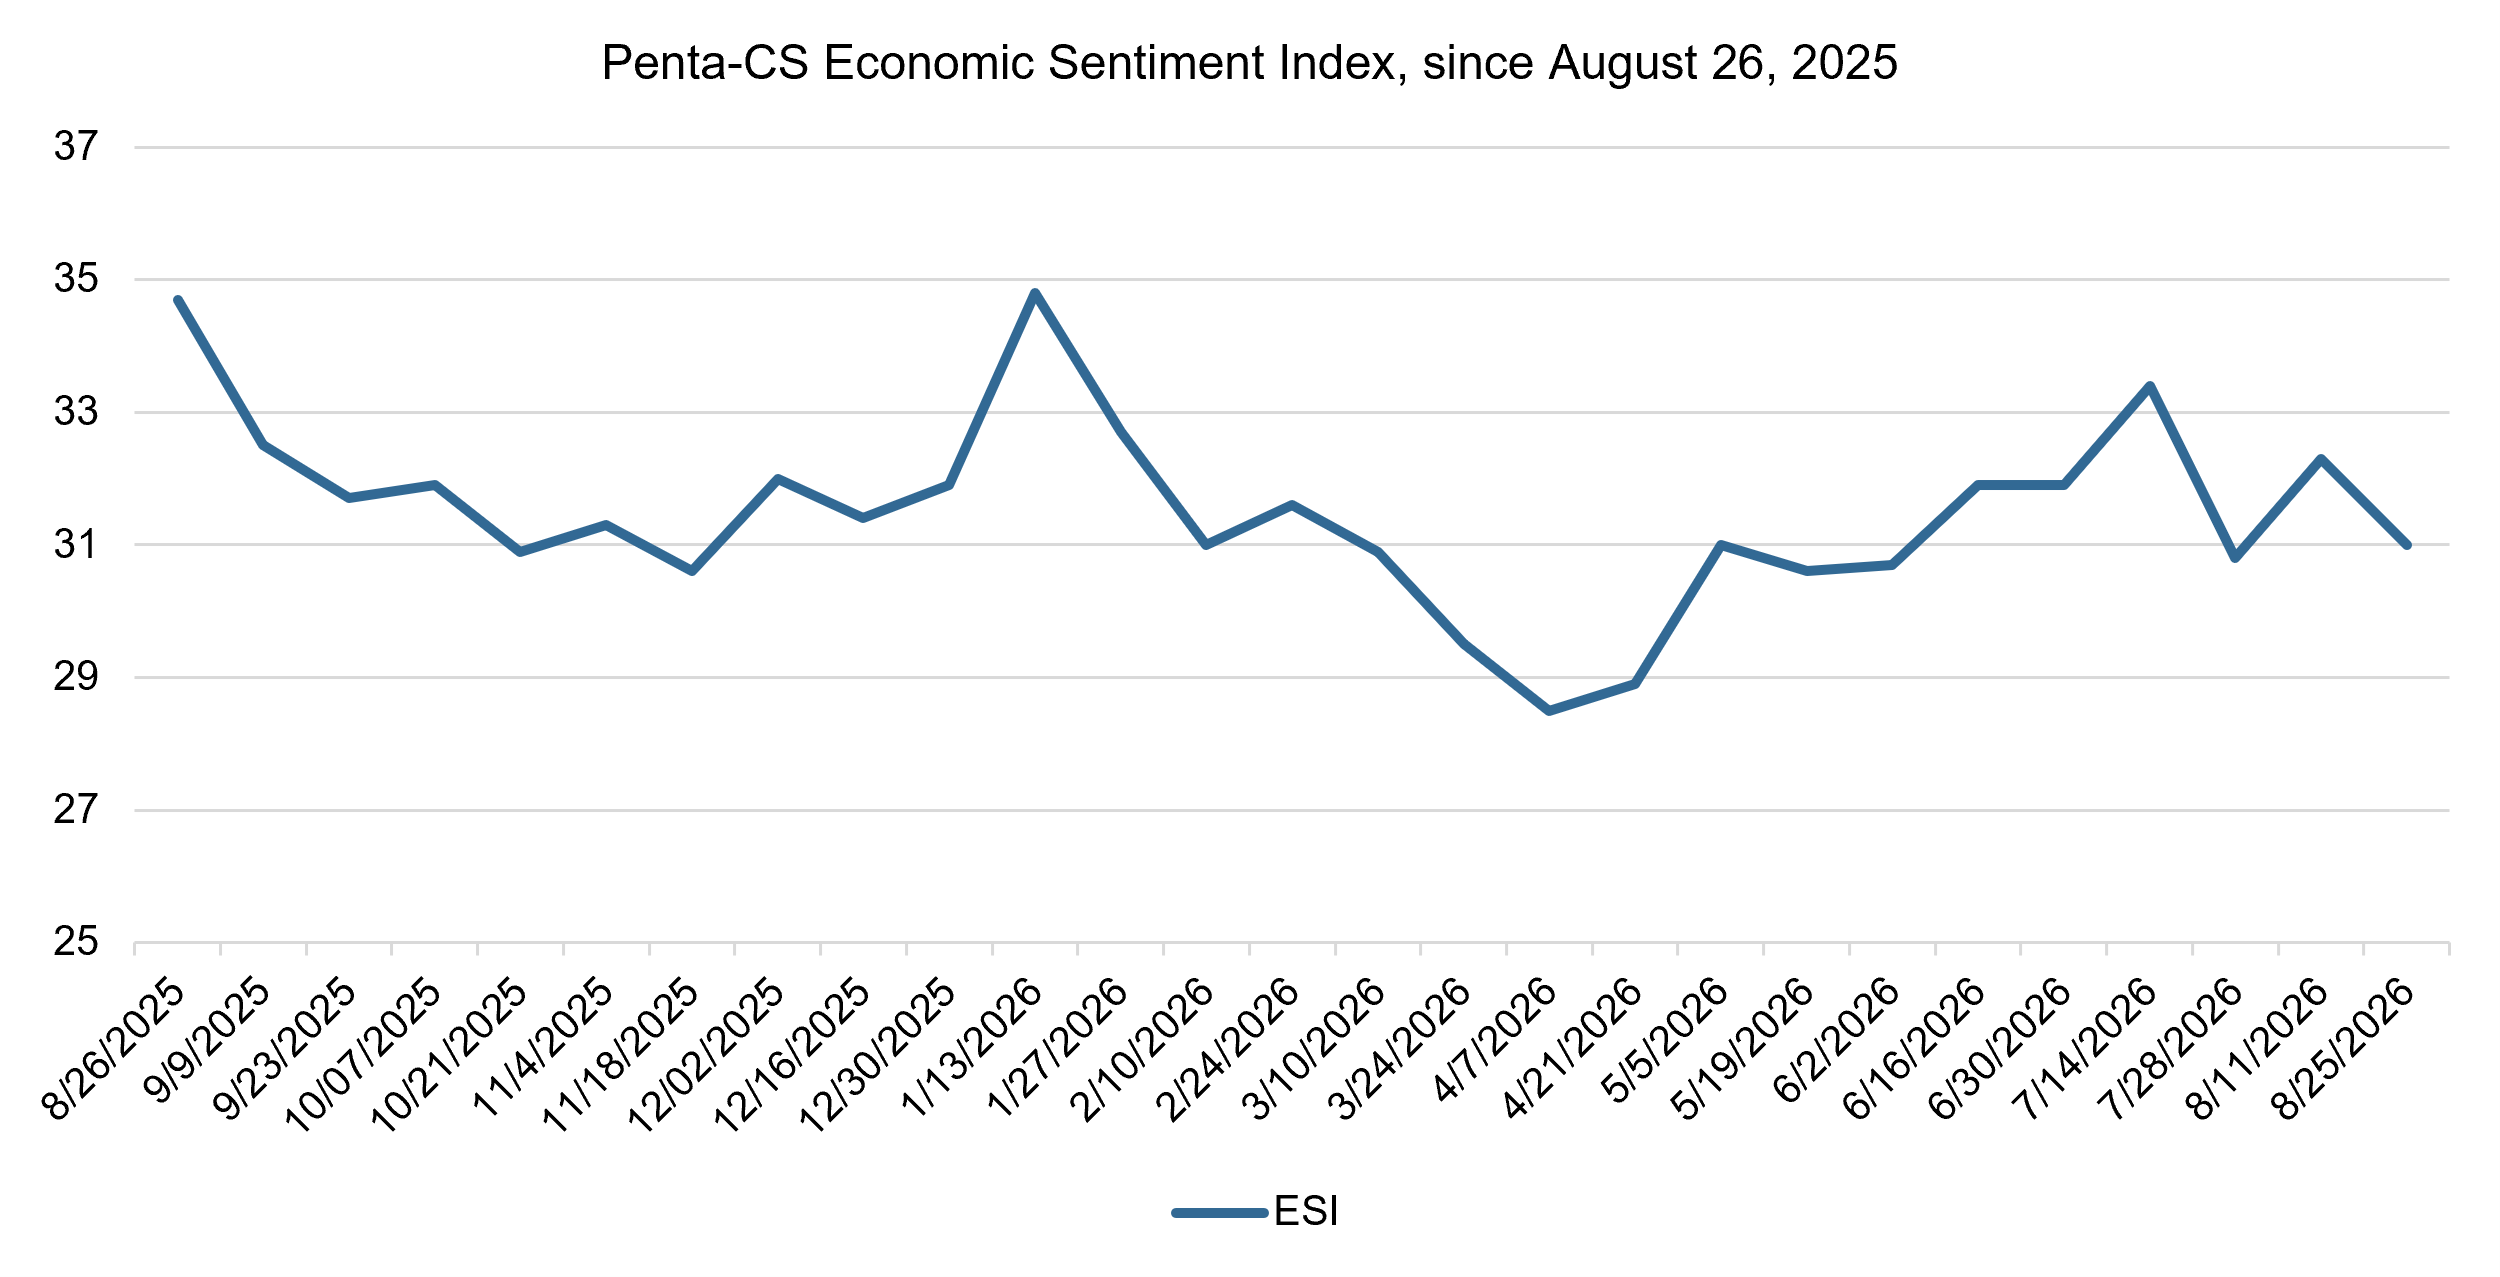
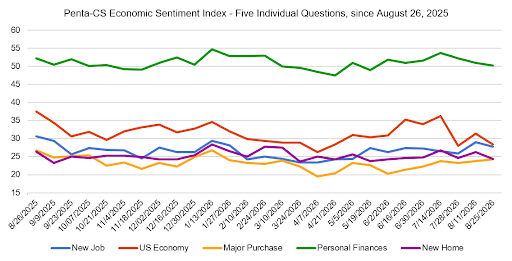
The latest biweekly reading of the Penta-CivicScience Economic Sentiment Index (ESI) decreased 1.3 points to 31.0, reversing some of the gains from the previous period after the U.S. national debt was announced to have exceeded $40 trillion.

Click to view image.

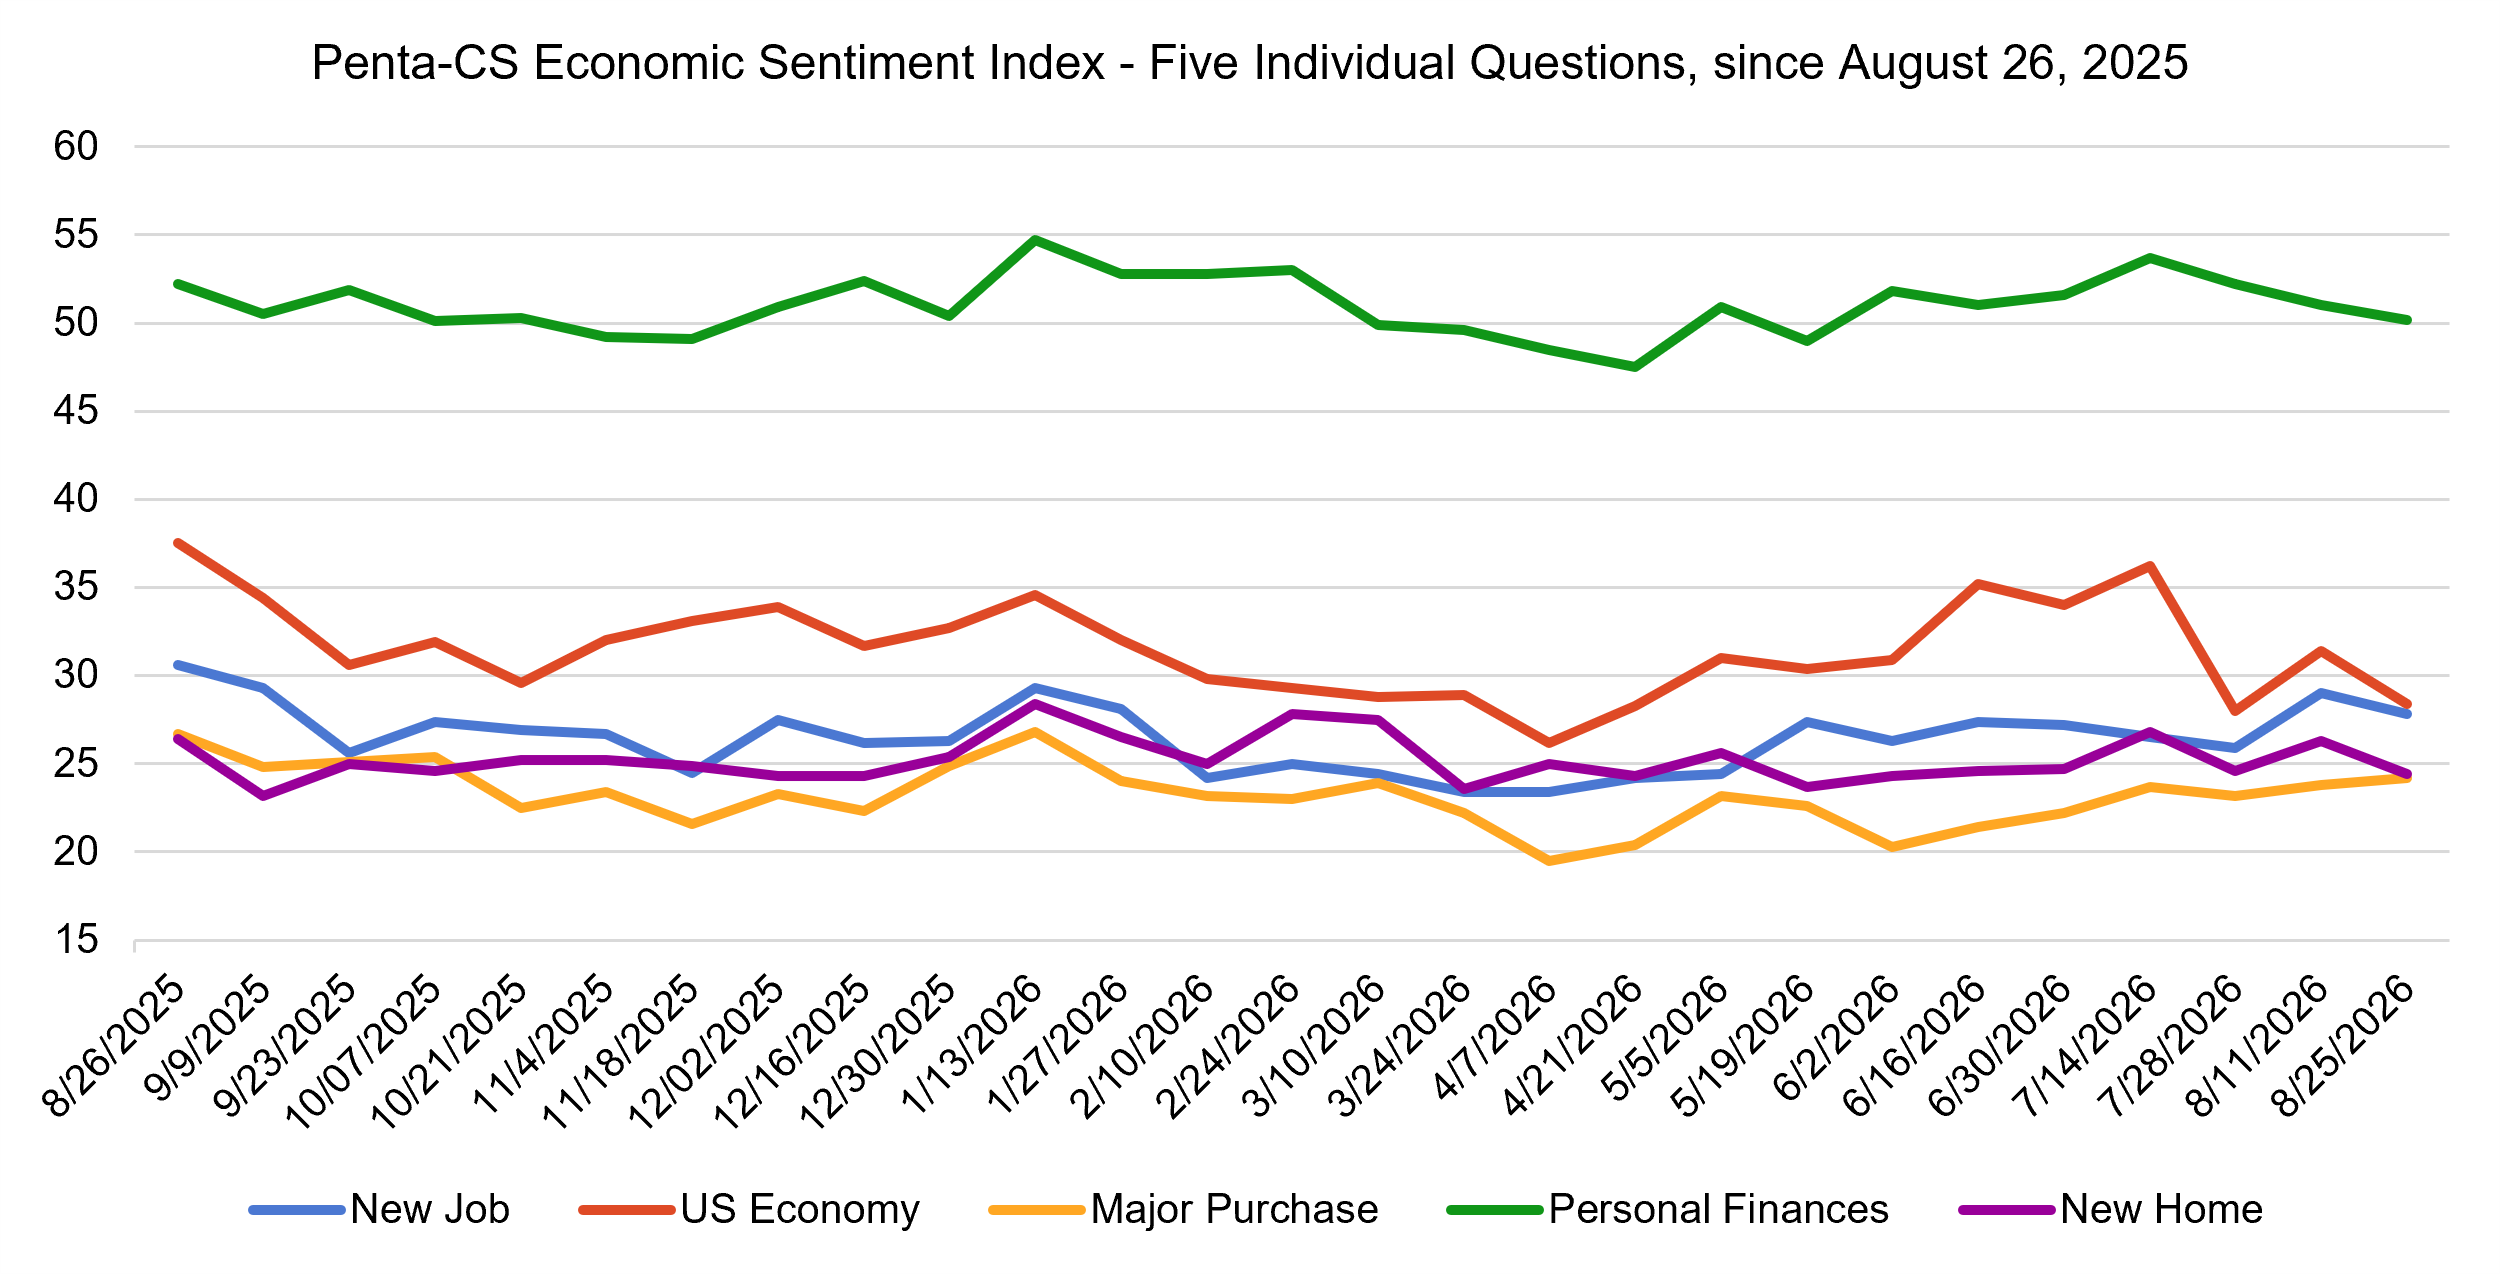
Four of the ESI’s five indicators decreased during this period. Confidence in the overall U.S. economy decreased the most, falling 3.0 points to 28.4.

—Confidence in buying a new home decreased 1.9 points to 24.4.

—Confidence in finding a new job decreased 1.2 points to 27.8.

—Confidence in personal finances decreased 0.8 points to 50.2.

—Confidence in making a major purchase increased 0.4 points to 24.2.

Click to view image.

Following news that the U.S. national debt exceeded $40 trillion, the yield on 30-year U.S. Treasury bonds reached 5.34 percent on August 18, its highest level since 2007, amid concerns about persistent inflation, growing federal debt, and the economic effects of the conflict in the Middle East. The selloff pushed borrowing costs higher across the economy and weighed on stocks, particularly technology shares. The Treasury Department responded by doubling the size of planned liquidity-support buybacks for longer-term debt, sending the 30-year yield sharply lower the following day.

Trade uncertainty also increased during the period. The White House implemented 50 percent tariffs on roughly $20 billion of Canadian goods following stalled trade negotiations, including certain alcohol, dairy, and motor vehicle imports. After briefly delaying implementation, the tariffs took effect on August 22, while Canada announced plans for retaliatory measures. Separately, the administration intensified economic pressure on Iran and countries that continue doing business with it. The move, dubbed “Operation Economic Outcast” by Treasury Secretary Scott Bessent, imposes new sanctions that target additional Iran-linked entities and threatens secondary sanctions against countries maintaining financial ties with Tehran.

Earlier in the period, the Bureau of Labor Statistics reported that the July Consumer Price Index (CPI) rose 0.1 percent from the previous month and 3.4 percent from a year earlier, down from a 3.5 percent annual increase in June. Core inflation, which excludes volatile food and energy prices, rose 0.2 percent for the month and 2.5 percent year over year. Energy prices fell 1.5 percent, helping offset increases in shelter and food costs, although they remain nearly 15 percent higher than this time last year. Furthermore, inflation outpaced wage growth for the fourth consecutive month as wages grew 3.2 percent in July. 

Consumer spending also weakened in July. The Census Bureau showed that U.S. retail sales fell 0.6 percent, the largest drop in over a year, following a 0.2 percent increase in June. Nevertheless, sales remained 5.0 percent higher than a year earlier. The decline added to signs that elevated prices and borrowing costs may be weighing on consumers even as spending remains above last year’s levels.

Click to view image.

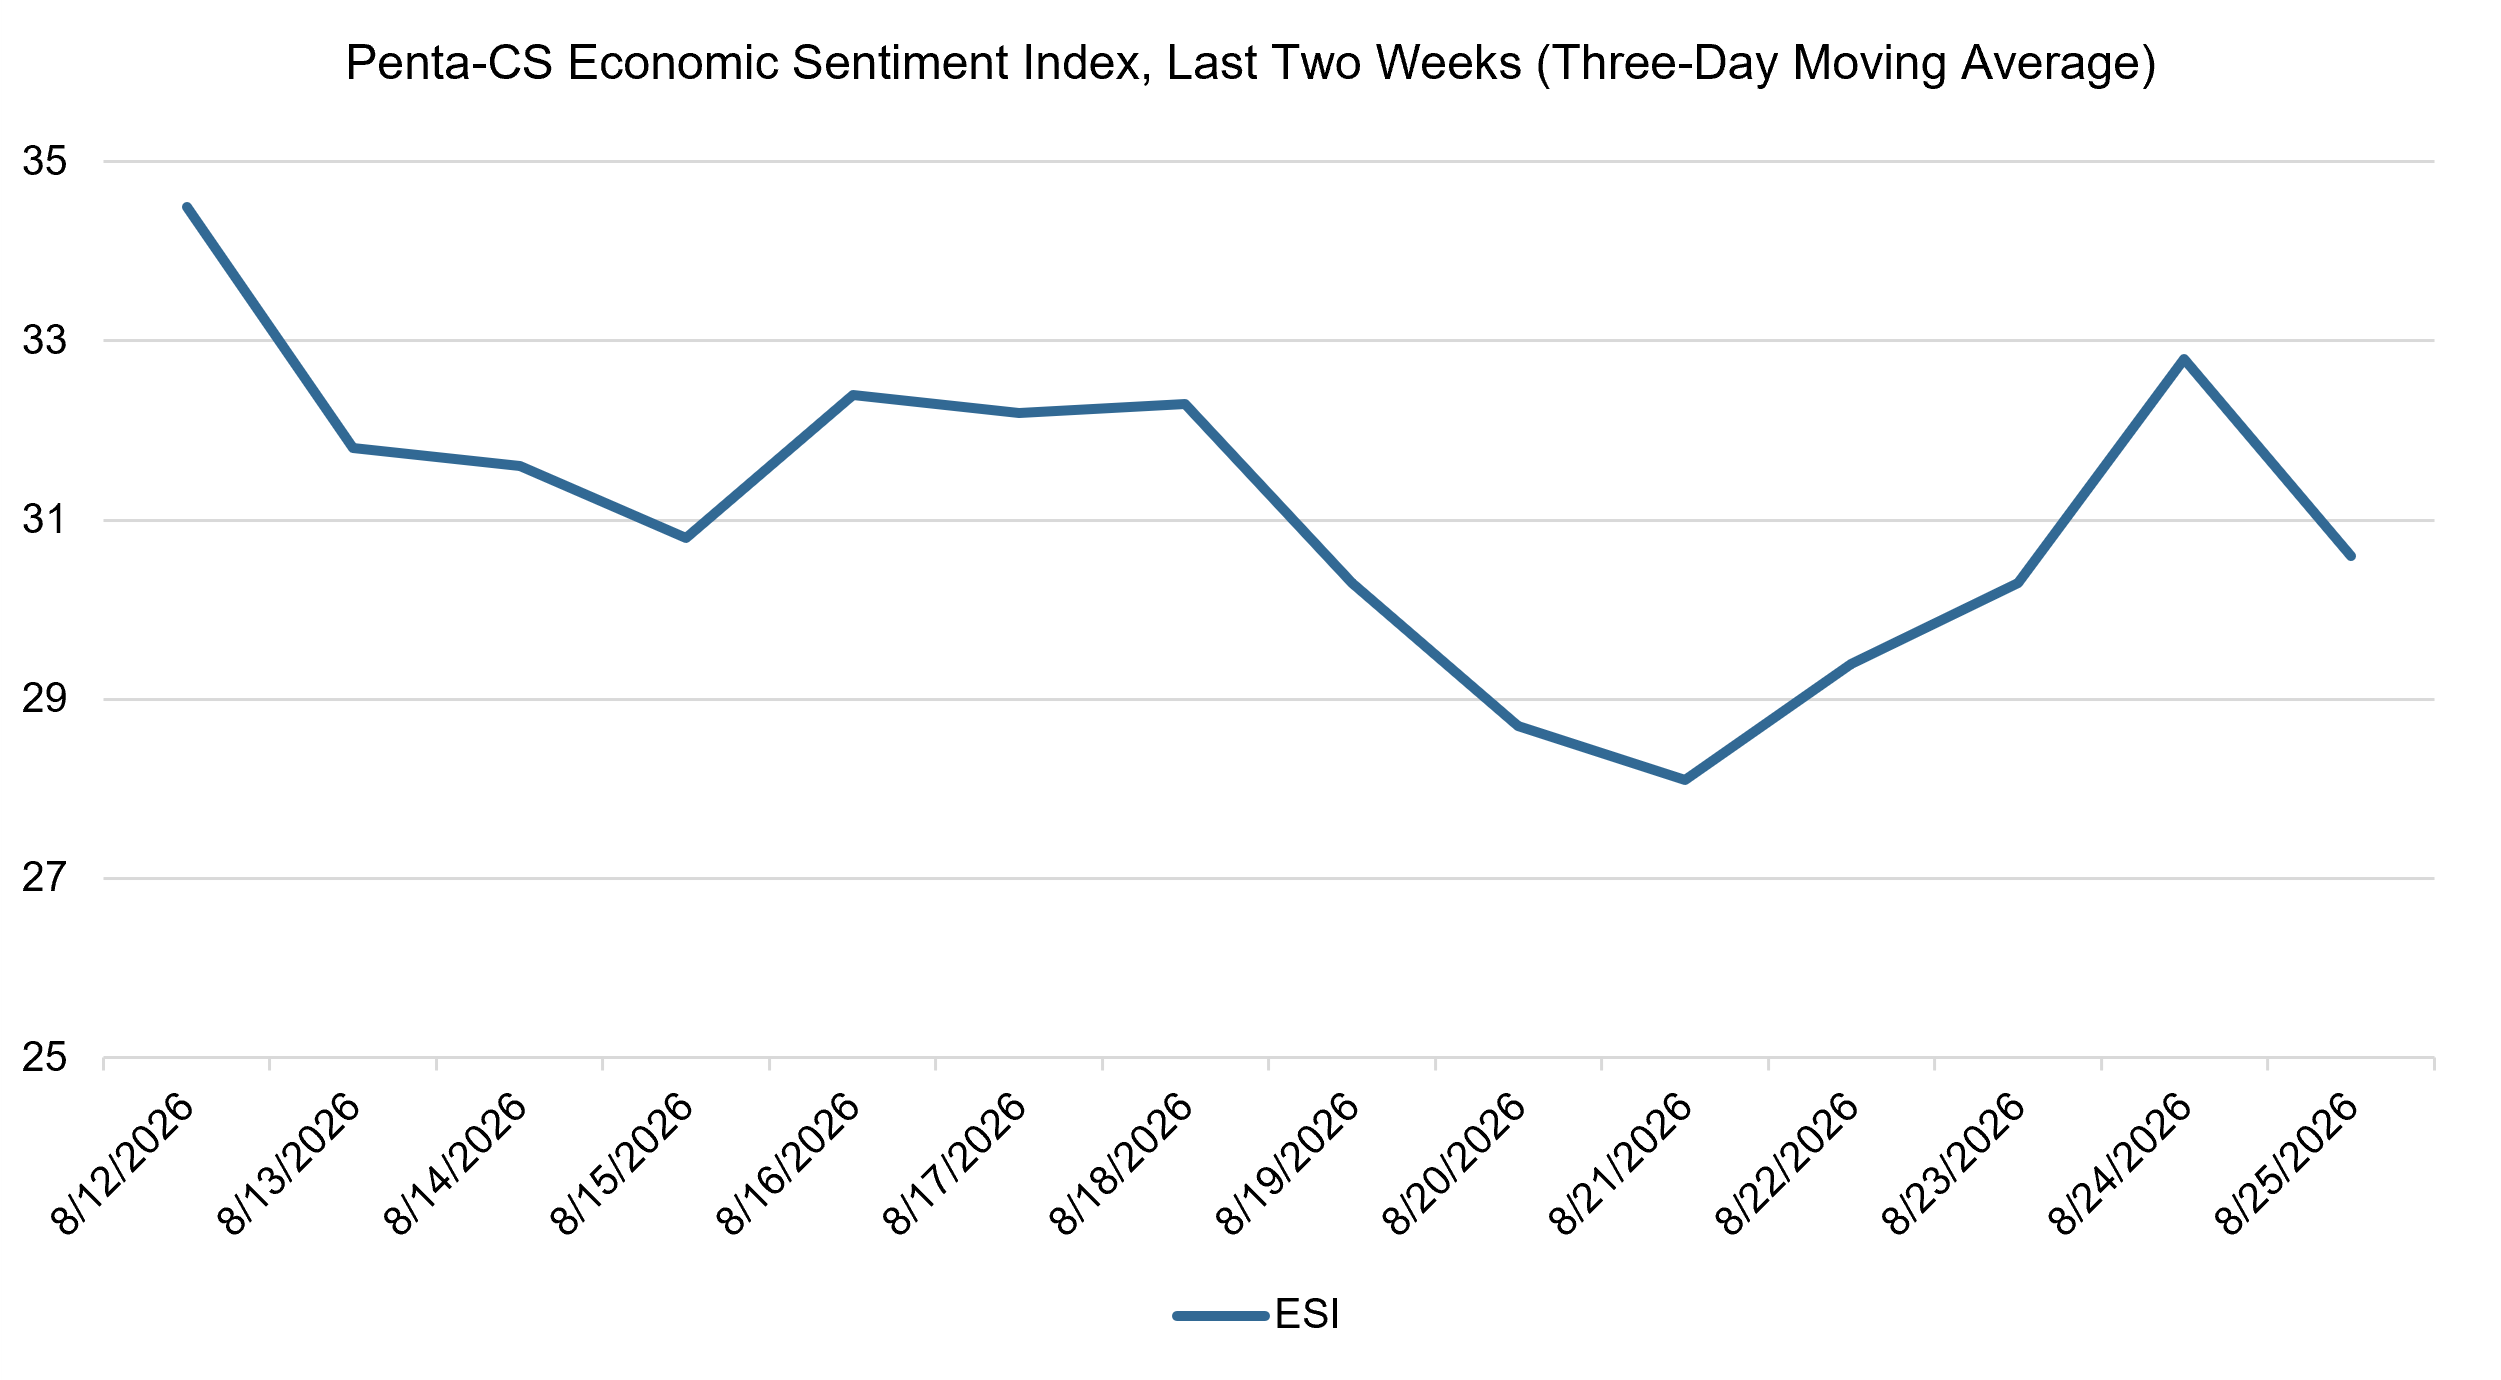
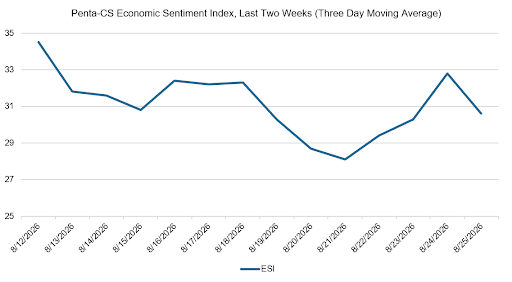
The ESI’s three-day moving average trended downward over the two-week period. It began at a high of 34.5 on August 12 and then fell to 30.8 on August 15 before slightly rebounding to 32.4 on August 16. It remained relatively steady until another decline that began August 19 that reached a period low of 28.1 on August 21. It then climbed to 32.8 on August 24 before falling back down to 30.6 on August 25 to close out the session.

The next release of the ESI will be on Wednesday, September 9, 2026.